Powerwell Holdings Berhad (PWRWELL) has landed its largest-ever contract—a combined RM190.4 million purchase order from a returning multinational customer for low-voltage switchgear and related equipment destined for a data centre project in Johor. Deliveries are scheduled to run across FY27f–FY28f, with project completion targeted for 4Q28, according to research published by Malacca Securities on 22 September 2026.
The award is a watershed moment for the mid-cap electrical equipment manufacturer. PWRWELL’s unbilled orderbook has surged to an all-time high of RM459.3 million, up from RM268.9 million as at end-June 2026—a jump of 71%, lifting revenue cover to approximately 2.9x FY26 revenue versus just 1.7x previously.
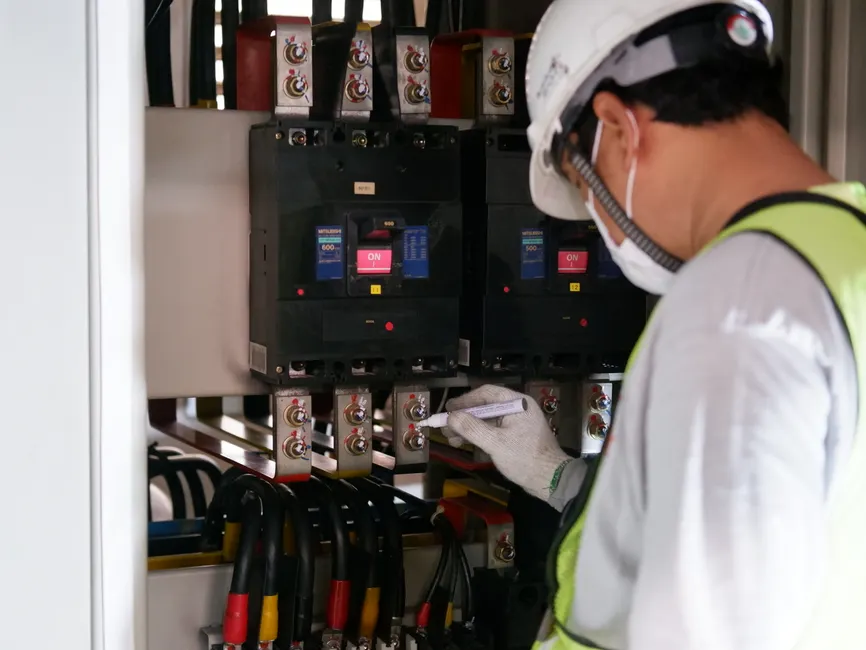
What Powerwell Holdings Does
PWRWELL manufactures and supplies low-voltage switchgear, electrical power distribution equipment, and related systems. The group has built a specialised track record in serving data centre operators and multinational infrastructure clients requiring mission-critical power distribution hardware.
The latest win from a returning customer underscores PWRWELL’s ability to secure repeat business and demonstrates that clients are confident enough to place large orders with the company—a strong signal of execution quality and service delivery.
Orderbook Win Replenishes FY27–FY28 Visibility
According to Malacca Securities, PWRWELL’s major contract wins year-to-date total RM349.2 million, representing 91.9% of the research house’s RM380 million orderbook replenishment assumption. This means only around RM30.8 million in new orders remains to be secured to hit the original forecast.
The enlarged orderbook materially de-risks earnings forecasts for the next two financial years. Malacca Securities noted that with such a substantial portion of assumed replenishment now locked in, visibility into FY27f–FY28f earnings has improved markedly, and further order wins would represent upside to current projections.
The research house also highlighted that PWRWELL’s ongoing manufacturing expansion is well-timed. Greater in-house production capacity should reduce outsourcing reliance and boost operating leverage as utilisation ramps up from FY28f onwards.
Valuation: P/E Re-rating to 20.0x
Malacca Securities has upgraded PWRWELL to BUY with a target price of RM1.41, according to M+ Online. The research house raised its applied P/E multiple to 20.0x from 17.0x, applied to mid-FY28f earnings per share of 7.07 sen.
The higher multiple reflects improved earnings visibility, reduced orderbook replenishment risk, and PWRWELL’s strengthening exposure to data centre power infrastructure. With 91.9% of FY27f orderbook replenishment already secured, Malacca Securities believes the previous “execution discount” in the valuation is less warranted.
The research house also pointed to an attractive growth-to-valuation profile: PWRWELL’s projected FY26A–FY29f core earnings compound annual growth rate of 26.1% translates into a price-to-earnings-growth (PEG) ratio of approximately 0.8x at 20.0x P/E, supporting the valuation re-rating.
Notably, Malacca Securities maintained its earnings forecasts, as the RM190.4 million contract win falls within the research house’s existing orderbook replenishment assumptions—meaning no upward earnings revisions, but stronger confidence in their delivery.
Risks and Headwinds
Malacca Securities flagged three downside risks to its BUY recommendation. First, slower-than-expected contract replenishment could leave orderbook coverage thinner than currently modelled.
Second, delays in project delivery or customer acceptance could push revenue recognition into later periods, impacting near-term earnings. Third, foreign exchange volatility could pressure margins if the customer contract is denominated in foreign currency or if inputs are sourced offshore.
What This Means for Retail Investors
For retail investors tracking PWRWELL, the contract award marks a turning point: from an orderbook perspective, the stock has moved from relying on new deals to secure revenue growth, to now having two years of visible revenue locked in. This reduces guesswork and makes earnings forecasting easier.
The upgrade to BUY and 20x P/E multiple from Malacca Securities reflects confidence that the stock has moved past its previous “show-me” phase. However, investors should monitor execution closely—whether PWRWELL can deliver these large orders on time and within quality standards will determine whether the valuation multiple sticks.
The data centre exposure is also relevant: if Malaysia’s data centre buildout accelerates (particularly around hyperscaler facilities), repeat wins from similar customers could drive earnings upside. Conversely, any slowdown in regional data centre capex could reduce PWRWELL’s growth runway.
Key Takeaways
- PWRWELL secured a landmark RM190.4 million contract, its largest ever, from a returning multinational data centre customer, with deliveries across FY27f–FY28f.
- Unbilled orderbook surged to RM459.3 million (all-time high), providing 2.9x revenue cover and materially improved earnings visibility into FY27–FY28.
- YTD contract wins of RM349.2 million represent 91.9% of orderbook replenishment assumptions, de-risking the earnings forecasts.
- Malacca Securities upgraded PWRWELL to BUY with a target price of RM1.41, raising the P/E multiple to 20.0x to reflect improved visibility and reduced execution risk.
- Execution on schedule and quality, foreign exchange movements, and future orderbook replenishment remain key monitoring points for investors.
Disclosure: This article summarises a research report published by Malacca Securities (M+ Online) on 22 September 2026. All ratings, target prices, and forecasts cited are those of Malacca Securities and are not recommendations from this publication. Investors should read the full report at https://mplusonline.com/research-report/detail/1437 before making investment decisions.
Source & Attribution
This article summarises a research report published by Malacca Securities Sdn Bhd (M+ Online) on 22 September 2026. All ratings, target prices and forecasts belong to Malacca Securities Research, not to the author of this blog.
Read the original report: M+ Online Research Report | View full PDF
Further Reading
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice or a recommendation to buy or sell any security. Ratings and target prices cited are those of Malacca Securities Research and are subject to change. Always do your own research before making investment decisions.
Want access to full M+ Online research reports and AI stock analysis? Contact Dexter Chia, AI-Driven Remisier at Malacca Securities Sdn Bhd. M+ Global Invitation Code: UBZQ | WhatsApp: +60169059789 | Why Choose Dexter?