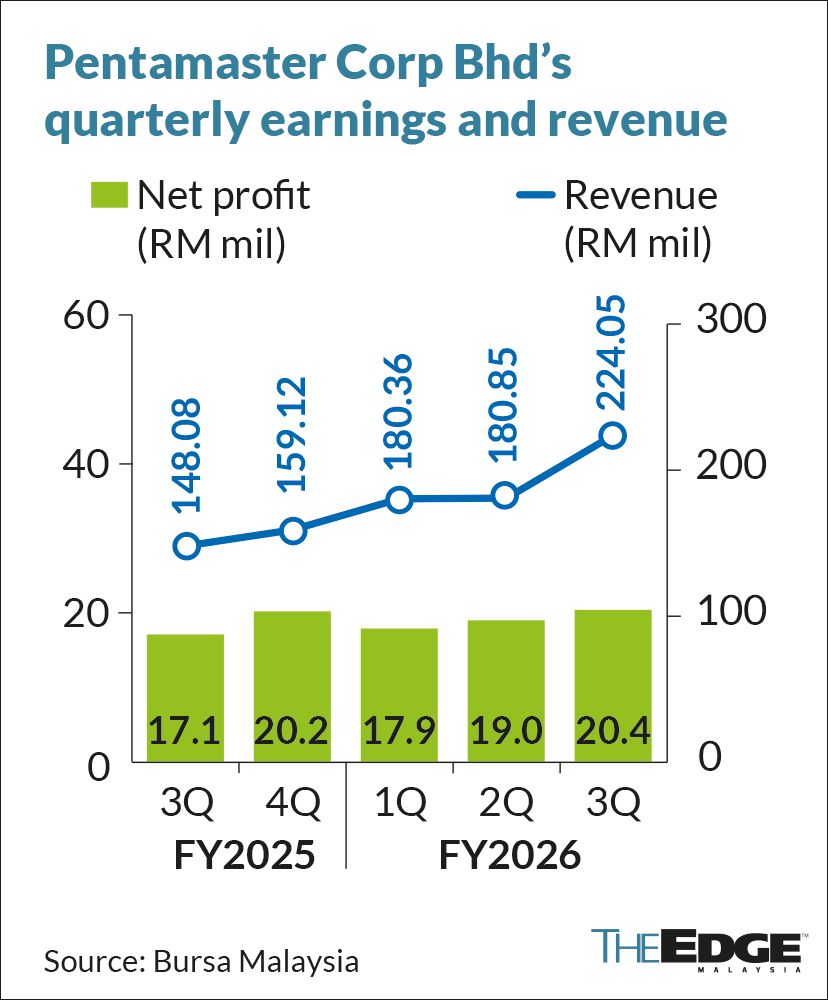
Pentamaster posted a 19.6% rise in third-quarter net profit, lifting it to RM20.46 million from RM17.11 million a year earlier. The Penang-based automation equipment maker’s Pentamaster 3Q net profit growth came on stronger demand for factory automation solutions (FAS) from the artificial intelligence (AI) computing sector.
What Drove the Pentamaster 3Q Net Profit Rise?
Revenue surged 51.3% to RM224.05 million from RM148.08 million in the quarter. Management credited better operating leverage, stronger absorption of fixed overheads and a more favourable sales mix with improved project margins.
The nine-month picture is stronger still:
- 9MFY2026 net profit: up 37.4% to RM57.42 million from RM41.79 million.
- 9MFY2026 revenue: up 37.9% to RM585.27 million from RM424.56 million.
- Profit after tax: RM85.57 million, approaching the RM91 million achieved in FY2025.
Nine-month revenue has already passed the RM583.68 million recorded for the whole of FY2025.
Which Segments Are Pulling Pentamaster’s Revenue?
The FAS segment remained the largest contributor, with revenue up 68.9% to RM171.63 million from RM101.64 million. Deliveries of automation solutions for AI server assembly production lines drove the jump.
The automated test equipment (ATE) segment grew 31.2% to RM50.60 million from RM38.56 million. Higher deliveries in the automotive and electro-optical sectors, plus contributions from AI Compute, supported the gain.
Is Healthcare Dragging Pentamaster Down?
Yes, healthcare revenue fell 39.3% to RM5.92 million from RM9.74 million. The segment’s pre-tax loss widened to RM6.4 million from RM3.8 million, reflecting lower medical device sales and differences in customer order volumes and delivery schedules.
What Backs Pentamaster’s Double-Digit Revenue Forecast?
Datuk Chuah Choon Bin, co-founder and group executive chairman, said: “Backed by a RM500 million outstanding book order, we expect to achieve a double-digit percentage growth over 2025.” The RM500 million order book is the main support for that target.
By customer segment, AI Compute contributed RM108.12 million, or 48.3% of third-quarter revenue. Medical contributed RM62.33 million (27.8%), and automotive contributed RM32.15 million (14.3%).
What Does Pentamaster’s FY2027 Revenue Mix Look Like?
Chuah expects AI computing, covering advanced chip and system packaging, to make up about 48% of group revenue in FY2027. Medical is projected at 28%, while automotive power silicon carbide and electro-optical businesses are expected to contribute a combined 20%.
Pentamaster is renovating about 120,000 sq ft of unused production space at its Campus 3 facility in Batu Kawan, Penang. The third plant will house AI chip and medical equipment production, and capital expenditure for 2027 is about RM30 million.
Why Did Pentamaster Shares Fall 7.71% to RM5.15?
On Thursday, Pentamaster (KL:PENTA) shares closed 43 sen, or 7.71%, lower at RM5.15. That valued the group at RM3.67 billion.
The shares fell on the same day the results were filed, but the source article does not link the two. Investors tracking AI-linked names can compare valuations using this AI Stock Analysis for Malaysians guide.
Key Takeaways
- 3QFY2026 net profit rose 19.6% to RM20.46 million, and revenue rose 51.3% to RM224.05 million.
- FAS revenue jumped 68.9% to RM171.63 million, and AI Compute made up 48.3% of third-quarter revenue.
- Healthcare revenue fell 39.3%, and its pre-tax loss widened to RM6.4 million.
- The RM500 million order book underpins the double-digit FY2026 growth target, with capex of about RM30 million planned for 2027.
📊 On AI Stock Terminal: PENTA quarterly results · PENTA announcements
Disclaimer: This article is for general information only and does not constitute investment advice. All figures come from Pentamaster’s bourse filing as reported by The Edge. Do your own research before making any investment decision, and consider your own risk tolerance.
Frequently Asked Questions
What was Pentamaster’s net profit for 3QFY2026?
Pentamaster’s net profit rose 19.6% to RM20.46 million for the three months ended Sept 30, 2026, from RM17.11 million a year earlier.
Is Pentamaster expecting double-digit revenue growth for FY2026?
Yes. Datuk Chuah Choon Bin expects double-digit percentage growth over 2025, backed by a RM500 million outstanding order book.
How much is Pentamaster worth on Bursa Malaysia?
Pentamaster shares closed at RM5.15 on Thursday, down 7.71%, which valued the group at RM3.67 billion.
How much capital expenditure does Pentamaster plan for 2027?
Pentamaster expects capital expenditure of about RM30 million in 2027. The spending supports the Campus 3 expansion in Batu Kawan, Penang, mainly for AI Compute and medical operations.
Source: View Original Article — The content is based on the original publisher. Refer to the original content for accurate info. Contact us for any changes.
Related Articles & Resources
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Always do your own research before making investment decisions.
Want to invest in Bursa Malaysia or US markets? Contact Dexter Chia, an AI Driven Remisier who has 2,300+ clients at Malacca Securities Sdn Bhd (M+ Global). M+ Global Invitation Code: UBZQ | WhatsApp: +60169059789 | Why Choose Dexter?