KJTS Group has staged a breakout above its one-year downtrend, and Malacca Securities Research has flagged RM1.14 and RM1.32 as the next price levels on the chart. The call, published on 6 November 2026, pairs the technical view with company catalysts that the research house believes could support a re-rating.
What KJTS Group Does
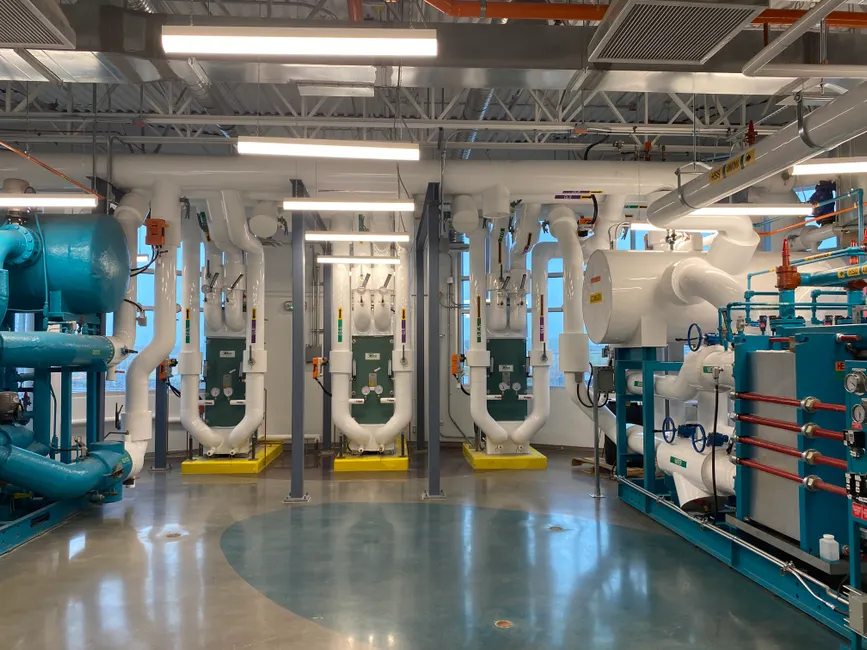
According to Malacca Securities Research, KJTS Group Berhad is built around cooling assets, with recurring operations and maintenance income forming a key part of its earnings profile. The company is also pushing into energy efficiency, including waste-heat recovery solutions through its iHandal unit.
The research house also highlights a push into mission-critical cooling for regional data centres. That expansion is linked to decarbonisation mandates under NETR, and KWAP is cited as an institutional partner.
Thailand Concessions and the RM48m Revenue Visibility
The most concrete catalyst in the report is a set of four 20-year cooling contracts in Thailand, signed with Centel. Malacca Securities Research estimates these lock in about RM48 million in high-margin recurring operations and maintenance revenue, alongside upfront works scheduled from September 2026.
The research house argues that multi-year cash flow visibility of this length strengthens KJTS’s regional scale. It sees that visibility as a basis for an upward valuation re-rating.
Technical Setup: Breakout, Momentum and Price Levels
The chart shows a bullish crossover above converging exponential moving averages, following a double bottom that produced a higher low. According to Malacca Securities Research, this pattern signals a positive reversal and possible continuation.
Momentum indicators support the setup. The RSI has edged above 50, while the MACD is forming a rounding bottom, which the research house describes as a potentially exponential breakout. Its stated upside levels are RM1.14 and RM1.32, provided momentum persists.
Margin Expansion and Valuation Basis
Malacca Securities Research expects momentum to accelerate in the second half of the year, driven by accretive contributions from iHandal’s waste-heat recovery business. The research house links expanding operating margins and higher-quality recurring income to a possible valuation multiple expansion alongside the breakout.
The summary of the report does not break out detailed earnings forecasts or the valuation multiples behind the upside levels. Readers who want the numerical basis should consult the full document directly.
Risks to the Setup
The most explicit risk in the report is technical: a break below RM0.920 would invalidate the breakout thesis. The research house also notes that sustaining the move depends on contract momentum providing enough liquidity to absorb overhead supply.
Execution risk sits on top of that. Revenue visibility from the Thailand contracts and the second-half margin story both depend on timely delivery, and the report does not quantify how much of group earnings they represent.
What This Means for Retail Investors
The report gives retail investors a clear set of reference points: RM1.14 and RM1.32 on the upside, RM0.920 on the downside. Those levels are the research house’s framework, not a forecast guaranteed to play out.
Investors weighing the call will want to check the full Malacca Securities document for the rating, assumptions and earnings detail behind it. The full report is available from M+ Online at mplusonline.com/research-report/detail/1496.
Key Takeaways
- Malacca Securities Research says KJTS Group has broken above a one-year downtrend, with RM1.14 and RM1.32 as upside levels.
- The invalidation level is a break below RM0.920, according to the research house.
- Four 20-year Thailand cooling contracts with Centel are cited as securing about RM48 million in recurring O&M revenue.
- Momentum signals include RSI above 50 and a rounding bottom in the MACD.
- iHandal’s waste-heat recovery business is expected to drive second-half margin gains, per the report.
Frequently Asked Questions
What price targets has Malacca Securities set for KJTS Group?
Malacca Securities Research has identified RM1.14 and RM1.32 as the upside levels for KJTS Group, provided momentum holds. The research house frames these as technical reference points rather than a separate valuation exercise.
How much revenue do the Thailand contracts add for KJTS Group?
According to Malacca Securities Research, the four 20-year cooling contracts with Centel lock in about RM48 million in high-margin recurring O&M revenue. Upfront works are scheduled from September 2026, the research house said.
What would invalidate the KJTS Group breakout setup?
The research house states that a break below RM0.920 would invalidate the setup. That level sits well below the upside targets, marking the boundary of the bullish technical view.
📊 On AI Stock Terminal: KJTS quarterly results · KJTS announcements
Source & Attribution
This article summarises a research report published by Malacca Securities Sdn Bhd (M+ Online) on 06 November 2026. All ratings, target prices and forecasts belong to Malacca Securities Research, not to the author of this blog.
Read the original report: M+ Online Research Report | View full PDF
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice or a recommendation to buy or sell any security. Ratings and target prices cited are those of Malacca Securities Research and are subject to change. Always do your own research before making investment decisions.
Want access to full M+ Online research reports and AI stock analysis? Contact Dexter Chia, AI-Driven Remisier at Malacca Securities Sdn Bhd. M+ Global Invitation Code: UBZQ | WhatsApp: +60169059789 | Why Choose Dexter?