GTA Holdings Berhad is Malaysia’s sole authorised supplier for Safran helicopter and EPI fixed-wing engines, a duopoly position that Malacca Securities sees as the bedrock of a 65.7% upside case from current IPO levels. The research house published its initiation report on 24 August 2026, flagging exclusive maintenance, repair and overhaul (MRO) certifications as a multi-year competitive moat that prospective rivals would struggle to replicate.
What GTA Holdings Does
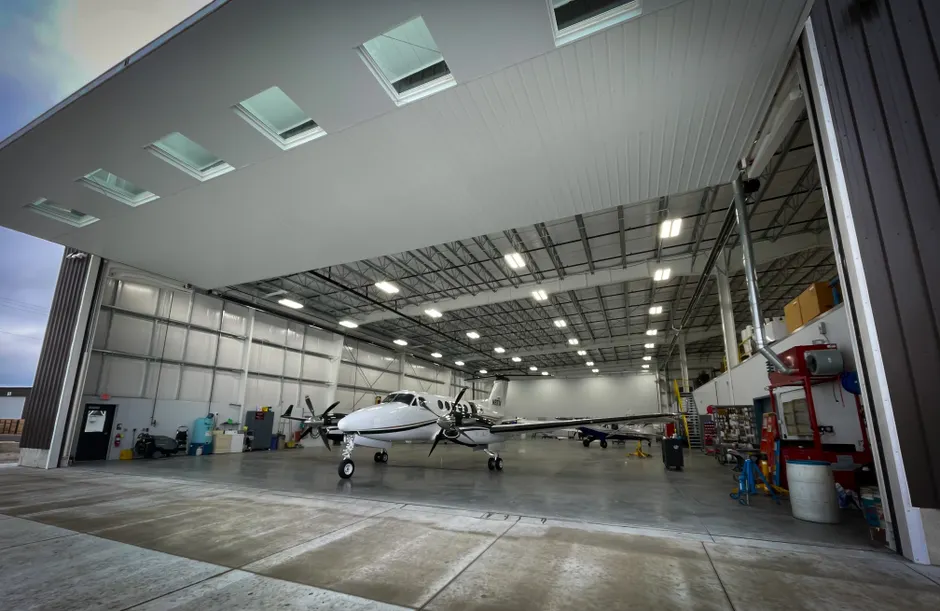
GTA operates in two core business streams: MRO services for helicopter and fixed-wing aircraft engines, parts and components, plus the sale of new aviation equipment including engines, engine modules and spare parts. The Group serves both military and civil aviation customers through long-term contracts including Availability Support Packages (ASP), Power-by-the-Hour (PBH) agreements, and In-Service Support (ISS) arrangements, with the Malaysian Ministry of Defence accounting for the bulk of revenue.
Through its subsidiary Global Turbine Asia, GTA holds dual OEM certifications: it is the sole Safran Certified Maintenance Centre and sole EPI Approved Maintenance Organisation in Malaysia. Malacca Securities noted that obtaining such dual certifications requires multi-year processes involving extensive capital investment, technical capability demonstration, and regulatory approvals from the Civil Aviation Authority of Malaysia (CAAM), the Directorate General of Civil Aviation (DGTA), and the European Aviation Safety Agency (EASA)—barriers that effectively lock out competitors.
Revenue Visibility and Government Contracts Anchor Projections
Mindef Service Branch 1 and Branch 2 collectively contributed 92.1% of FY25 revenue and 95.4% of FPE26 revenue, according to the report. The Group secured a 5-year extension for its Heavy Helicopter Engine 1 ASP contract in 2023 and signed an ISS prime contractor appointment for Fixed-wing Engine 1 support the same year, providing visibility into medium-term cash flows.
Malacca Securities projects 3-year earnings CAGR of 6.6%, with core PATMI expected to reach RM40.8 million to RM48.9 million over the forecasted period. The research house said the Group’s MRO capability has expanded from Level 1 MRO for a single helicopter engine in 2012 to covering 7 Safran products (5 helicopter engines and 2 APUs) and EPI’s Fixed-wing Engine 1 by the listing prospectus date.
Expansion into Landing Gear and Geographic Markets
GTA allocated RM5.9 million (8.2% of IPO proceeds) toward expanding MRO capability into landing gear, wheels and brakes—a move Malacca Securities sees as opening a new layer of recurring maintenance revenue. The research house also flagged RM10.0 million (13.9% of IPO proceeds) earmarked for geographic expansion into the Middle East via joint venture arrangements and Brunei via a Safran HE distributor partnership targeted for end-2026.
The Brunei expansion is notable because it will be serviced directly from existing Malaysian facilities, limiting capex intensity while leveraging the Group’s existing infrastructure and certifications. Malacca Securities said this positions GTA to monetise its technical capabilities across wider Southeast Asian and Middle Eastern aviation markets without material incremental fixed costs.
Valuation and Fair Value Target
Malacca Securities assigned a fair value of RM0.58 per share based on a P/E ratio of 17.0x applied to FY27f EPS of 3.42 sen. This implies 65.7% upside from the RM0.35 IPO price, representing a substantial margin of safety relative to the initial public offering valuation.
The 17.0x multiple reflects the quality of GTA’s contract revenue mix and competitive positioning, though the research house did not elaborate extensively on peer comparisons or methodological nuances in the report summary provided.
Key Risks to Monitor
Concentration risk remains material: two government customers supply over 95% of revenue, meaning any contraction in Ministry of Defence procurement could materially impact earnings. Malacca Securities did not explicitly quantify this risk, but it is a structural feature inherent to the business model.
Execution risk on geographic expansion and landing gear MRO certification represents a second headwind: delays in Middle East JV structuring or Brunei regulatory approval could slow revenue diversification and defer expected earnings contributions. The research house also did not disclose GTA’s track record on capex project execution or MRO capability expansion timelines in the summary.
What This Means for Retail Investors
Retail investors evaluating GTA at IPO levels should weigh the attractiveness of long-term government contract visibility and exclusive OEM certifications against the concentration risk posed by dependence on two Mindef service branches. Malacca Securities’ 65.7% upside target suggests the stock has room to run, but that assumes the Group executes on capability and geographic expansion without material delay or cost overrun.
The RM0.58 target is meaningful context for position-sizing; investors should compare it against broader Bursa Malaysia aviation and defence-related peer valuations and consider their own risk tolerance around government customer dependency. The research house’s BUY initiation does not guarantee near-term performance, and execution on RM5.9 million landing gear capex and RM10.0 million Middle East JV investments will determine whether the 6.6% earnings CAGR materialises.
For the full report, visit Malacca Securities M+ Online.
Key Takeaways
- Malacca Securities maintains BUY with RM0.58 fair value target, implying 65.7% upside from RM0.35 IPO price.
- Dual OEM certifications (Safran and EPI) create a multi-year competitive moat that competitors cannot easily replicate.
- Mindef contracts underpin strong revenue visibility, but 92-95% customer concentration is a material risk.
- RM5.9m landing gear expansion and RM10.0m Middle East JV capex target new revenue streams and reduce government dependency over time.
- Projected 3-year earnings CAGR of 6.6% hinges on execution of geographic and capability expansion plans.
Source & Attribution
This article summarises a research report published by Malacca Securities Sdn Bhd (M+ Online) on 24 August 2026. All ratings, target prices and forecasts belong to Malacca Securities Research, not to the author of this blog.
Read the original report: M+ Online Research Report | View full PDF
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice or a recommendation to buy or sell any security. Ratings and target prices cited are those of Malacca Securities Research and are subject to change. Always do your own research before making investment decisions.
Want access to full M+ Online research reports and AI stock analysis? Contact Dexter Chia, AI-Driven Remisier at Malacca Securities Sdn Bhd. M+ Global Invitation Code: UBZQ | WhatsApp: +60169059789 | Why Choose Dexter?