Butterfield FB Berhad commissioned its second coffee and tea blending line in January 2026 and a dedicated 312 MT matcha production line in February 2026, setting the stage for what Malacca Securities sees as a multi-year earnings acceleration. The research house projects core PATMI will climb to RM33.4 million, RM38.4 million and RM47.8 million in FY27, FY28 and FY29 respectively, underpinned by volume growth, customer expansion and operating leverage across an enlarged production footprint.
A Specialised B2B Beverage Ingredient Play
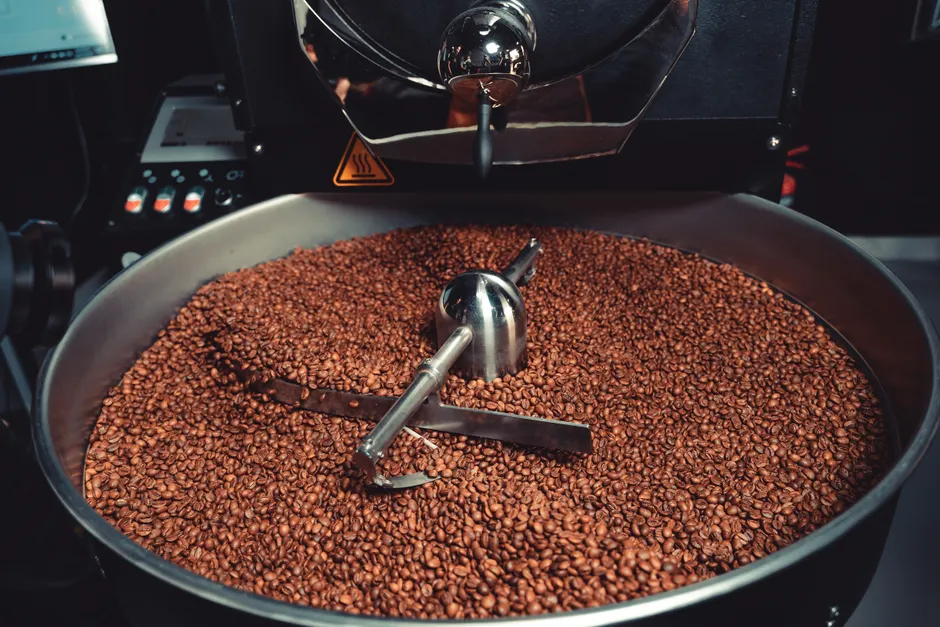
BFIELD manufactures customised coffee and tea extract powder blends for F&B manufacturers and business end users, with a portfolio spanning 98 coffee formulations and 53 tea formulations. Beyond core manufacturing, the company trades 315 food ingredient SKUs — spanning dairy, non-dairy products, food additives, cocoa and plant-derived powders across Malaysia, Cambodia, China and Thailand — alongside 55 instant beverage premix SKUs including instant coffee, tea and cocoa blends sold in Malaysia and Thailand.
Customer stickiness appears embedded in the business model: Aik Cheong Group has been a client for 17 years and accounts for 16.6% of FY26 revenue, suggesting that switching suppliers would require replicating proprietary formulations, taste profiles and quality specifications. Malacca Securities highlighted this as a competitive moat, citing the formulation depth and established relationships as barriers to customer attrition.
Manufacturing Capacity: The Engine of Growth
Current capacity stands at two coffee and tea lines with combined annual capacity of 8,190 MT plus a dedicated 312 MT matcha line. According to Malacca Securities, total capacity will rise from 5,538 MT in FY26 to 8,502 MT in FY27 and FY28, then expand to 10,891 MT in FY29 as the fourth line ramps on a prorated basis, reaching 12,597 MT upon full commissioning.
The expansion is backed by RM15.2 million in IPO proceeds earmarked for the Bukit Minyak Premises, comprising RM12.5 million for construction and RM2.7 million for machinery. Malacca Securities emphasised that utilisation rates and sales execution — not capacity alone — will determine how quickly this translates into earnings growth.
Matcha as a Premiumisation Play
The dedicated matcha line, operational since February 2026, offers what Malacca Securities views as a strategic opportunity beyond its initial revenue contribution. Management has flagged matcha and tea extract powder blend expansion as a key growth strategy over the next 24 months, providing an avenue to participate in premium tea applications and deepen wallet share among existing F&B customers.
This matters because BFIELD has historically been coffee-weighted: matcha diversifies the product mix and allows the company to serve higher-margin premium segments. Malacca Securities sees this as relevant to both revenue diversification and margin trajectory.
Margin Expansion and Operating Leverage
BFIELD‘s gross profit margin expanded from 18.8% in FY23 to 21.7% in FY26, while PAT margin improved from 9.7% to 12.9% over the same period. More importantly, manufacturing GP margin climbed to 19.9% in FY26 from 17.7%, while manufacturing revenue grew 15.9% to RM212.6 million, signalling that margin expansion is no longer dependent on the higher-margin trading segment alone.
Malacca Securities expects further operating leverage as newly installed capacity matures, with earnings growth driven by a combination of higher sales volumes, improving utilisation and a progressively richer product mix. This operating leverage story sits at the heart of the 16.3% CAGR thesis.
Valuation and M&A Optionality
According to Malacca Securities, the RM0.63 target price is derived by applying a 14.0x P/E multiple to mid-FY28f EPS of 4.49 sen, implying 31.3% upside from the IPO price of RM0.48. The research house has not assumed meaningful M&A contributions in its base case, though BFIELD has allocated RM13.0 million (18.1% of gross IPO proceeds) towards strategic investments and acquisitions, with management specifically eyeing instant beverage premix brand owners and manufacturers.
Successful M&A execution — whether expanding premix capacity or improving value chain integration — could serve as a re-rating catalyst, though this remains a catalyst rather than a base case assumption in Malacca Securities’ projections.
What This Means for Retail Investors
BFIELD is a newly listed small-cap play in a niche but defensible segment: B2B beverage ingredients for established F&B customers. The investment case hinges on three pillars: (1) proven customer relationships and sticky revenue; (2) tangible new capacity with clear medium-term ramp visibility; and (3) operating leverage as utilisation improves.
For retail investors accustomed to larger-cap stocks, this represents a higher-risk, higher-growth profile. The company is not yet profitable at scale — core PATMI is projected at RM33.4 million in FY27 — and execution risk on capacity utilisation and new customer wins is material. Malacca Securities’ 31.3% upside assumes successful capacity ramp-up and near-term earnings expansion; execution shortfalls would compress that return sharply.
The matcha diversification and M&A optionality provide potential upside surprises, but neither is guaranteed. Retail investors should treat this as a growth story that rewards patience — and punishes execution failures.
Key Takeaways
- Malacca Securities projects core PATMI CAGR of 16.3% through FY29, reaching RM47.8 million, driven by newly commissioned manufacturing lines ramping to utilisation.
- Manufacturing capacity expands from 5,538 MT (FY26) to 12,597 MT (full commissioning), though the research house emphasises utilisation rates and sales execution as the key variables, not capacity alone.
- Gross profit margin improved to 21.7% in FY26 from 18.8% in FY23, with manufacturing GP margin now contributing to the margin expansion story alongside the trading segment.
- Malacca Securities assigns a RM0.63 target price using 14.0x P/E on mid-FY28f EPS, implying 31.3% upside from the RM0.48 IPO price based on a three-year earnings CAGR thesis.
- RM13.0 million earmarked for M&A in instant beverage premix represents a potential second leg of growth beyond organic capacity expansion, though not factored into base case projections.
The full Malacca Securities research report on Butterfield FB Berhad is available at M+ Online. Retail investors should review the complete analysis and risk factors before making investment decisions. This article summarises the research house’s publicly stated views and does not constitute investment advice.
Source & Attribution
This article summarises a research report published by Malacca Securities Sdn Bhd (M+ Online) on 24 August 2026. All ratings, target prices and forecasts belong to Malacca Securities Research, not to the author of this blog.
Read the original report: M+ Online Research Report | View full PDF
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice or a recommendation to buy or sell any security. Ratings and target prices cited are those of Malacca Securities Research and are subject to change. Always do your own research before making investment decisions.
Want access to full M+ Online research reports and AI stock analysis? Contact Dexter Chia, AI-Driven Remisier at Malacca Securities Sdn Bhd. M+ Global Invitation Code: UBZQ | WhatsApp: +60169059789 | Why Choose Dexter?