This guide is for married couples, siblings, and adult children in Malaysia who want to build up shares as a family but are unsure how the CDS system actually allows this to happen. I wrote it after fielding the same questions again and again from clients at the counter and over WhatsApp.
Can a Couple or Family Share One CDS Account?
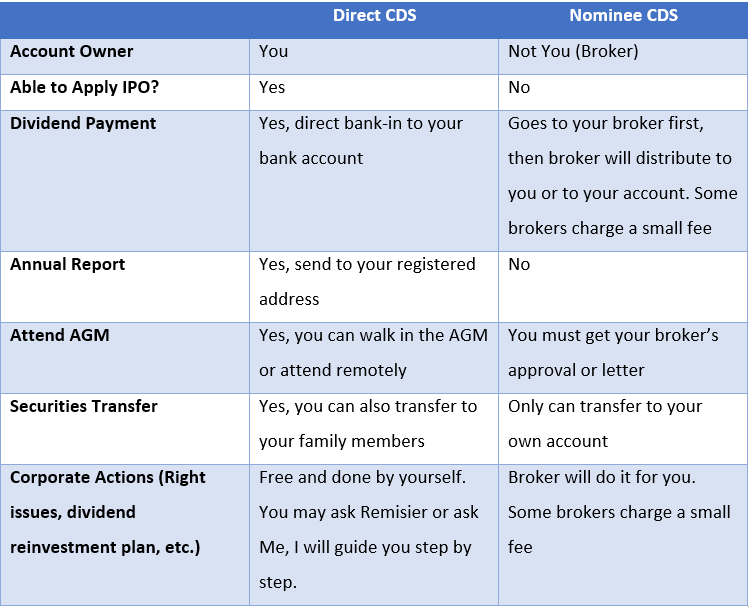
No. A CDS (Central Depository System) account is always registered to one named individual. Individual CDS accounts are opened in one person’s own name; joint CDS accounts are not offered to individual investors.
So a husband and wife cannot hold one CDS account together, and parents cannot hold a joint CDS account with an adult child. Each person who wants to hold shares in their own name needs their own separate CDS account.
How Couples Can Invest Together in Practice
Even though the account itself is individual, couples manage this well all the time. Here is the usual setup I recommend to clients:
- Each spouse opens their own CDS account and trading account with the broker.
- You agree together on a shared investing plan — how much to put in each month, which sectors or counters to focus on.
- Each person funds trades from their own bank account linked to their own trading account.
- You review the combined portfolio together at home, even though on paper they are two separate accounts.
The trip-up here is couples assuming they can top up one spouse’s trading account from the other spouse’s bank account without any issue. It is usually fine operationally, but keep it simple — pay from the account holder’s own bank account to avoid confusion later, especially at withdrawal time.
Moving Shares Between Family Members
Sometimes a client wants to move shares they already hold into a spouse’s or child’s CDS account — perhaps as a gift, or to consolidate holdings. This is possible, but it is a transfer, not a joint holding.
- Both the sender and receiver must already have their own active CDS accounts.
- Bursa Malaysia Depository only allows transfers between family members for certain relationships, so check with your broker that yours qualifies before you start.
- The transfer can be initiated through your broker, or self-service through the Bursa Anywhere app if both accounts are linked there.
- You will need to specify the counter and number of shares to move.
- Costs may apply depending on the type of transfer — check with your broker or on the M+ website before you proceed, as this varies by situation.
A common mistake is expecting the transfer to be instant like a bank transfer. It usually takes a bit of processing time, so don’t submit it the morning you need the shares in the other account.
Investing for Children Under 18
Children cannot open a CDS account in their own name until they are adults. If you want to start investing for a child, there are specific legal routes to do this properly.
I’ve written a separate guide on investing for your child that walks through exactly how this works and which route suits which family situation, so I won’t repeat it in full here. If you’re a parent wanting to start early for your child, that guide is the right next stop.
Planning Ahead: Records and Wills
Because every family member’s shares sit in a separate, individually named CDS account, this becomes a real issue if something happens to one person and the family doesn’t know what was held or where.
I always tell clients: keep a simple written record of every CDS account you hold, which broker it’s with, and roughly what’s in it. Share this record with a trusted family member, not just in your own head.
A will matters here too. Shares in a CDS account form part of your estate, and without a will, your family may face a longer and more complicated process to access or transfer them after you’re gone.
Comparing Family Investing Options
| Situation | What’s Allowed | What’s Not Allowed |
|---|---|---|
| Married couple investing | Two separate CDS accounts, coordinated plan | One joint CDS account for both spouses |
| Gifting shares to family | Transfer between two individual CDS accounts | Adding a second name to an existing account |
| Investing for a minor | Approved routes covered in our separate child-investing guide | A CDS account opened directly in the child’s name |
How I Manage Several Family Members’ Accounts
A good number of my 2,200-plus clients are actually family units — husband, wife, sometimes their adult children too. I can service all of them, but each account stays completely separate in the system.
In practice, I keep each person’s portfolio, mandates, and instructions distinct, even though I might discuss strategy with the whole family together over one call. Every trade instruction still has to come from the actual account holder, not a family member acting on their behalf, unless there’s a proper authorisation in place.
This separation is actually protective for the family — if a dispute or inheritance question ever comes up, there’s no ambiguity about whose shares are whose.
Common Mistakes to Avoid
Assuming a joint CDS account exists somewhere and asking the broker to “combine” two family members into one.
Letting one family member trade in another’s account without proper written authorisation on file.
Forgetting to keep any record of CDS accounts, so other family members have no idea what exists when it matters most.
Treating a share transfer between family members like an instant, cost-free bank transfer.
Delaying a will because shares “aren’t that much yet” — the account structure makes this a real practical issue for whoever is left to sort it out.
Key Takeaways
- Every CDS account in Malaysia is held by one individual — no joint accounts exist for couples or family.
- Couples invest together by each holding their own account and agreeing on a shared plan.
- Shares can be moved between family members’ CDS accounts via the broker or Bursa Anywhere, with possible costs to check beforehand.
- Investing for children under 18 requires specific legal routes — see our separate guide on that topic.
- Keep a personal record of all your CDS accounts and make sure you have a will.
- A remisier can service multiple family accounts while keeping each one fully separate and properly authorised.
Frequently Asked Questions
Can my spouse and I open a joint CDS account in Malaysia?
No, CDS accounts can only be held by one individual. You and your spouse would each open your own separate account and can still coordinate your investing as a couple.
How do I transfer shares to my spouse’s or child’s CDS account?
You submit a transfer request through your broker or through the Bursa Anywhere app if both accounts are linked, specifying the counter and quantity. Processing takes some time, so check with your broker on the current timeline and any applicable costs before assuming it’s instant.
What documents do I need to move shares between family members?
Typically you’ll need both parties’ CDS account details and identification, plus a completed transfer instruction form from the broker. Ask your broker for the exact current form and requirements, as these can be updated from time to time.
What happens to my CDS account if something happens to me?
Your shares remain in your CDS account and form part of your estate, to be dealt with according to your will or, if there isn’t one, the applicable distribution laws. This is why keeping a record of your accounts and having a proper will matters so much for your family.
Can I invest for my children before they turn 18?
You can start early, but not by opening a CDS account directly in a minor’s name. There are specific approved routes for this, which are covered in detail in our separate guide on investing for children in Malaysia.
If you’re trying to work out the right setup for your own family — whether that’s coordinating accounts with your spouse, transferring shares to a sibling, or getting started for your kids — reach out and I’ll walk you through it properly. I’m Dexter Chia, remisier at Malacca Securities Sdn Bhd, and you can open an M+ Global account with invitation code UBZQ or message me directly on WhatsApp at +60169059789.
Need Help With This?
If you are an M+ Online or M+ Global client and need help with this process, message me directly — I handle these requests for clients every week.
WhatsApp: +60169059789 | M+ Global Invitation Code: UBZQ
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Always do your own research before making investment decisions.
Want to invest in Bursa Malaysia or US markets? Contact Dexter Chia, an AI Driven Remisier who has 2,200+ clients at Malacca Securities Sdn Bhd (M+ Online / M+ Global). M+ Global Invitation Code: UBZQ | WhatsApp: +60169059789 | Why Choose Dexter?