Strategic Tie-Up Broadens Powerwell’s Data Centre Power Scope
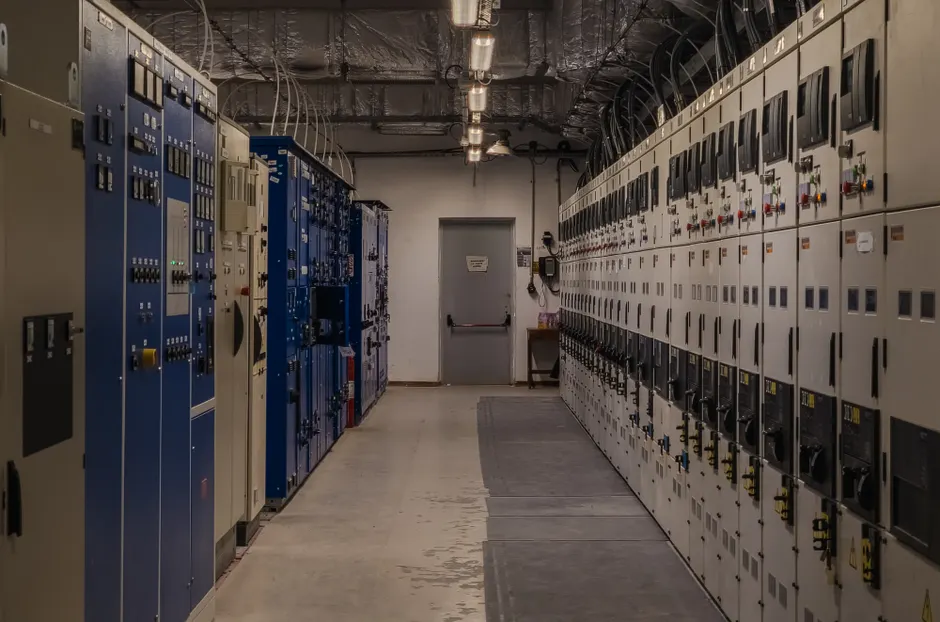
Powerwell Holdings has entered a one-year strategic collaboration agreement with Socomec Innovative Solution (Malaysia) to pursue large data centre and hyperscale opportunities across Malaysia. Through its wholly-owned subsidiary Powerwell International Sdn Bhd (PISB), the company will act as system integrator for power train units (PTUs) that incorporate Socomec’s uninterruptible power supply (UPS) systems.
The collaboration operates on a non-exclusive, project-by-project basis—meaning PWRWELL can still pursue independent opportunities while working with Socomec where synergies make sense. This pragmatic structure allows the company to layer additional capabilities onto its existing power distribution and system integration expertise without locking into a single supplier or losing flexibility.
What Powerwell Actually Does
PWRWELL designs, manufactures and distributes electrical switchgear and related power distribution equipment, traditionally serving industrial and commercial clients. The Socomec tie-up marks a strategic pivot deeper into the data centre power infrastructure value chain, where demand from Malaysia’s booming cloud computing and AI server sectors is exploding.
By combining PISB’s power distribution capabilities with Socomec’s UPS technology, the company can now offer more comprehensive, integrated PTU solutions to hyperscale data centre operators—essentially moving from supplying components to delivering complete power packages for mission-critical facilities.
The Numbers That Matter
The timing of this announcement is critical. Just days before the Socomec news, PWRWELL secured its largest-ever contract worth RM190.4 million, according to Malacca Securities. This single award lifted the company’s unbilled order book to RM459.3 million—a substantial backlog that provides earnings visibility.
Year-to-date major contract wins now total RM349.2 million, representing 91.9% of Malacca Securities’ FY27 replenishment assumption of RM380 million. Plainly put: the research house assumed PWRWELL would win RM380 million in new contracts this financial year, and the company has already secured nearly all of that—with months still remaining.
Malacca Securities projects core earnings growth at a compound annual rate of 26.1% through FY26 to FY29, implying a PEG ratio of approximately 0.8x at 20.0x price-to-earnings—a valuation metric that analysts use to assess whether growth-heavy stocks are expensive or cheap relative to their growth rate.
How Malacca Securities Values the Stock
According to Malacca Securities Research, the RM1.41 target price rests on 20.0x applied to mid-FY28 earnings per share of 7.07 sen. The research house chose a 20.0x multiple to reflect PWRWELL’s expanding exposure to data centre power infrastructure—a faster-growing market segment than traditional switchgear.
The Socomec collaboration reinforces this premium valuation assumption. By enabling PWRWELL to participate in additional projects and undertake broader PTU scope, the partnership strengthens the research house’s confidence in the company’s longer-term growth trajectory. With replenishment risk now moderated—given that nearly 92% of FY27 assumed order wins are already locked in—the earnings visibility has improved materially.
Risks to Watch
Malacca Securities identifies three key downside risks. First, slower-than-expected contract replenishment: if data centre capex spending cools or competitors win major tenders, order intake could disappoint. Second, delays in project delivery or customer acceptance: data centre projects are complex, and delays erode margins and push earnings recognition backward.
Third, foreign exchange volatility: PWRWELL operates across borders, and currency swings—particularly if the ringgit weakens—can compress profitability on foreign-currency-denominated contracts. None of these are imminent threats, but they merit monitoring over the coming quarters.
What This Means for Retail Investors
For retail investors tracking Malaysian industrials, PWRWELL represents a leveraged play on three converging tailwinds: Malaysia’s data centre infrastructure buildout, the country’s ambitions as a regional hyperscale hub, and strong corporate demand for power redundancy solutions. The Socomec partnership provides a concrete proof point that marquee global players see PWRWELL as a credible integration partner.
The company enters this growth phase with substantial order visibility—nearly half a billion ringgit in unbilled work—reducing uncertainty around near-term revenue. That said, replenishment will need to sustain at current levels for the 26% CAGR forecast to hold true. Investors should monitor quarterly contract wins and ask whether the pipeline remains robust beyond FY27.
Key Takeaways
- RM459.3 million unbilled order book provides substantial earnings visibility and reduces replenishment risk for FY27–FY28.
- Socomec collaboration positions PWRWELL to offer integrated power train unit solutions for large data centres, expanding its addressable market beyond switchgear.
- Malacca Securities maintains BUY rating and RM1.41 target price, premised on 20.0x FY28 EPS and 26.1% core earnings CAGR through FY29.
- Year-to-date contract wins of RM349.2 million already represent 91.9% of the research house’s full-year replenishment assumption, leaving limited room for order disappointment.
- Key risks include slower contract replenishment, project delivery delays, and ringgit volatility—all material to execution but not imminent.
Frequently Asked Questions
What exactly is Powerwell doing with Socomec?
Powerwell International Sdn Bhd will act as system integrator for power train units (PTUs) that combine Socomec’s uninterruptible power supply (UPS) systems with PWRWELL’s power distribution capabilities. The one-year collaboration is non-exclusive and project-by-project, targeting large data centre and hyperscale opportunities in Malaysia.
Is RM1.41 a realistic target price?
According to Malacca Securities Research, the RM1.41 target is based on 20.0x applied to mid-FY28 earnings per share of 7.07 sen. The research house adopted this 20.0x multiple to reflect the company’s expanding data centre exposure and faster growth profile compared to traditional switchgear. Whether the stock reaches this price depends on the company executing its order backlog and sustaining high contract win rates.
How much revenue is already locked in?
PWRWELL has an unbilled order book of RM459.3 million according to Malacca Securities, meaning this work has been won but not yet recognized as revenue. This provides substantial visibility into near-term earnings and reduces the risk of revenue disappointment in FY27–FY28.
What could go wrong with this investment thesis?
Malacca Securities flagged three risks: slower contract replenishment if data centre capex spending weakens, delays in project delivery or customer acceptance that push earnings recognition backward, and foreign exchange volatility that could compress margins on foreign-currency contracts.
Why did Malacca Securities choose a 20.0x earnings multiple?
The research house applied 20.0x to PWRWELL’s FY28 EPS to reflect the company’s expanding exposure to data centre power infrastructure, which it views as a faster-growing market segment than traditional industrial switchgear. This premium multiple is supported by the company’s 26.1% core earnings CAGR through FY29, which implies a PEG ratio of approximately 0.8x—suggesting the multiple is not stretched relative to growth.
Full Report: The complete Malacca Securities research report on Powerwell Holdings Berhad is available at M+ Online. Published 30 September 2026.
Source & Attribution
This article summarises a research report published by Malacca Securities Sdn Bhd (M+ Online) on 30 September 2026. All ratings, target prices and forecasts belong to Malacca Securities Research, not to the author of this blog.
Read the original report: M+ Online Research Report | View full PDF
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice or a recommendation to buy or sell any security. Ratings and target prices cited are those of Malacca Securities Research and are subject to change. Always do your own research before making investment decisions.
Want access to full M+ Online research reports and AI stock analysis? Contact Dexter Chia, AI-Driven Remisier at Malacca Securities Sdn Bhd. M+ Global Invitation Code: UBZQ | WhatsApp: +60169059789 | Why Choose Dexter?