What’s Driving the Construction Sector Rally?
RHB Research maintained its “overweight” call on construction on April 1, naming Gamuda, Sunway Construction and Binastra as sectoral top picks. Cement and ready-mixed concrete (RMC) prices had already started rising as early as November 2025, before the US-Israel versus Iran war erupted on Feb 28.
Retail pump diesel prices are up 88% year to date, while industrial diesel has surged 145%, from RM2.79/litre in February to RM6.85/litre. RHB projects that every 10% rise in diesel, cement and RMC costs could cut major contractors’ net margins by 0.5 to 0.7 percentage points (ppts), and if Brent crude stays between US$100 and US$150 a barrel for six months or longer, the hit could reach 3 to 4 ppts.
RHB assumes cement prices could be 6% to 10% higher and RMC 20% to 40% higher year-on-year. Builders may respond by using more steel bars relative to concrete, stockpiling materials, or negotiating cost-plus contracts instead of fixed lump-sum deals — RHB notes Gamuda already runs most of its overseas and data centre jobs on a cost-plus basis.
Adding to the pressure, tipper trucks carrying sand, cement and bricks are excluded from the Subsidised Diesel Control System 2.0 (SKDS 2.0), forcing operators to buy unsubsidised diesel at RM5.52/litre versus RM2.15/litre under the scheme. Construction machinery such as excavators also runs on industrial-priced diesel at RM6.85/litre versus the RM5.52/litre retail pump price.
Why Is IJM Corp in Focus After the Data Centre Win?
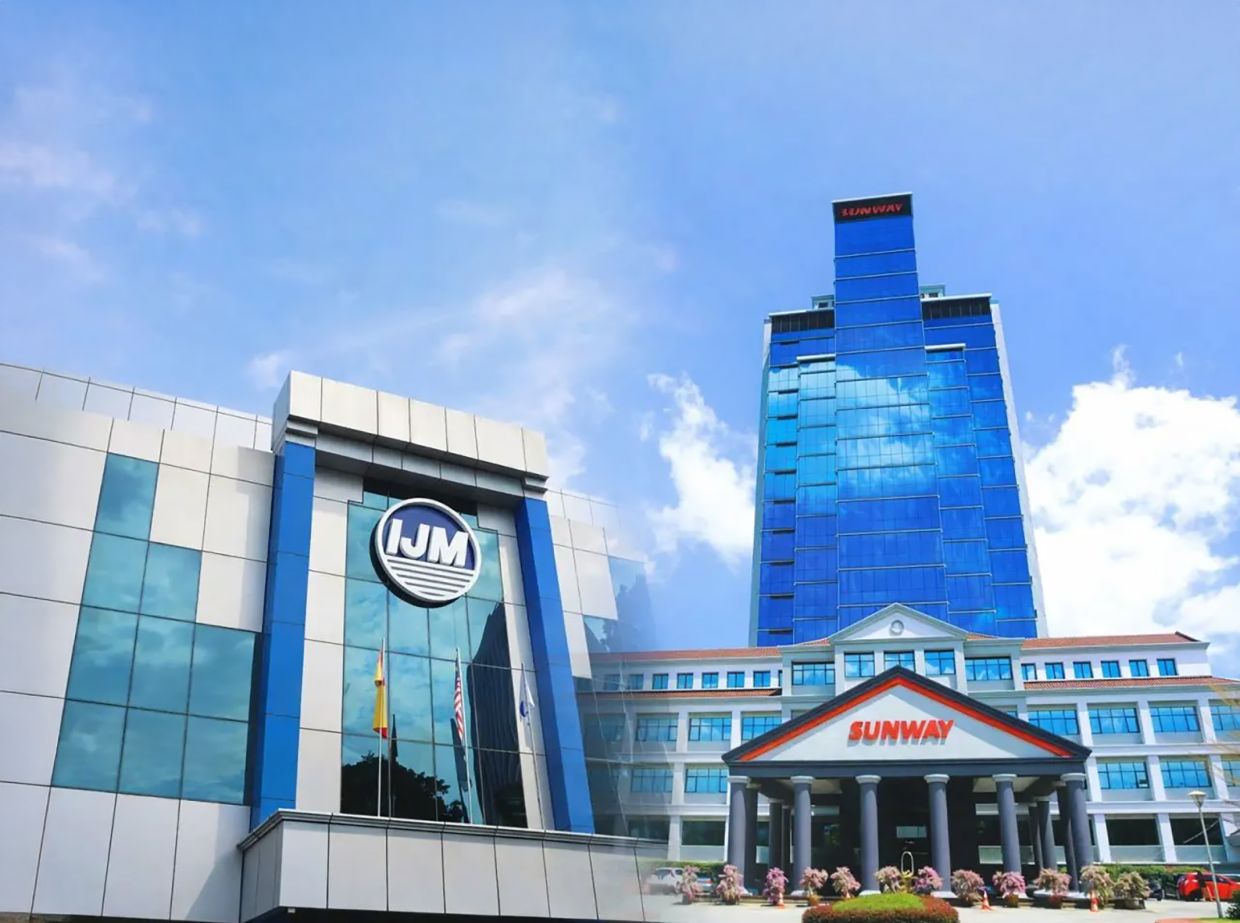
IJM Corp accepted a letter of award from Sime Darby Property for Package 2 main building works of a hyperscale data centre in Elmina Business Park, Selangor, worth RM658 million, CGS International Research noted on April 1. The win comes amid a potential takeover offer for IJM by Sunway Bhd, which CGS called “timely and meaningful” evidence of IJM’s construction franchise.
MACC confirmed on March 24 that its ongoing investigations do not relate to IJM itself but are confined to individuals associated with the company. CGS estimates data centres now make up 43% of IJM’s RM9.1 billion order book, while its RM17 billion tender book is dominated by data centre, commercial and industrial building jobs.
CGS retains an “add” call with a sum-of-parts target price of RM3.42, citing IJM’s spun concrete piles business and the fact that it trades at just 0.7 times FY26F book value. Rerating catalysts include a potential listing to unlock construction business value and stronger property sales, while risks include slower project awards and higher raw material costs.

How Is Capital A Positioned After Its Restructuring?
Following its PN17 restructuring, Capital A has disposed of its AirAsia short-haul aviation business across Malaysia, Thailand, Indonesia, the Philippines and Cambodia to AirAsia X, Hong Leong Investment Bank noted on March 31. This leaves Capital A’s remaining structure with limited direct exposure to rising global fuel prices.
The group still retains its Teleport logistics arm, which has direct jet fuel exposure through three owned freighters and indirect exposure via freight rates. Management indicated it can pass on higher costs given resilient air cargo and e-commerce demand.
Hong Leong IB sees ADE (Asia Digital Engineering), MRO, Teleport and the MOVE online travel agency as positioned for growth beyond the current conflict. It reiterated a “buy” call but lowered its sum-of-parts target price to 93 sen (from RM1.05), based on 15 times FY26 forward PER and a RM2.2 billion fair value for Capital A’s 19.5% stake in AAX; it expects the group’s PN17 status to be lifted by 2H26.
Why Did United Malacca Beat Expectations?
United Malacca posted 3QFY26 core net profit up 1.5% y-o-y to RM37.2 million despite flat revenue, as stronger Malaysian operations offset weaker Indonesian performance, TA Securities said on April 1. Over 9MFY26, core earnings jumped 51.5% y-o-y to RM127.1 million on a 15.9% revenue increase.
TA raised its FY26-FY28 earnings estimates by 16.5% to 21.4%, citing higher fresh fruit bunch growth assumptions and firmer crude palm oil (CPO) price assumptions. It also flagged that Middle East-driven increases in oil and freight costs are strengthening biodiesel economics and could accelerate Indonesia’s B50 programme, while precautionary buying across Asia is supporting near-term CPO prices.
TA maintained a “buy” call with a higher target price of RM7.34 (from RM7.29), rolling its valuation base year to 2027 on a 13 times PER multiple plus a 3% ESG premium.
What Should Bursa Investors Watch Next?
Diesel-linked cost pressure on contractors, the progress of IJM’s potential takeover by Sunway, Capital A’s PN17 exit timeline, and CPO price trends are the key variables flagged across these reports. Retail investors comparing these names against sector peers may find it useful to cross-check broker views with Malaysia’s AI-driven stock analysis tools.
Given the differing risk profiles — cost-sensitive construction margins, restructured aviation-linked logistics, and commodity-driven plantation earnings — using different account types can help separate shorter-term positions from longer-term holdings. Before acting on any broker target price, running your own deeper AI-powered stock analysis can help contextualise these figures against your own portfolio.
Key Takeaways
- RHB Research maintains “overweight” on construction but warns diesel-driven cost increases could cut contractor net margins by up to 3-4 ppts if Brent stays at US$100-150/barrel for six months or more
- IJM Corp secured a RM658 million data centre package from Sime Darby Property; CGS International keeps an “add” call with a RM3.42 target price, noting data centres are 43% of IJM’s RM9.1 billion order book
- Capital A retains a “buy” call from Hong Leong IB, though the target price was cut to 93 sen after the AirAsia short-haul business was disposed of to AirAsia X
- United Malacca’s 9MFY26 core earnings rose 51.5% y-o-y to RM127.1 million; TA Securities raised its target price to RM7.34 on stronger CPO and FFB growth assumptions
- Tipper trucks and construction machinery remain excluded from subsidised diesel pricing under SKDS 2.0, adding to input cost pressure across the construction sector
📰 Source: View Original Article — The content is based on the original publisher. Refer to the original content for accurate info. Contact us for any changes.
📚 Related Resources from Dexter Chia
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Always do your own research before making investment decisions.
Want to invest in Bursa Malaysia or US markets? Contact Dexter Chia, an AI Driven Remisier who has 2,200+ clients at Malacca Securities Sdn Bhd (M+ Global). M+ Global Invitation Code: UBZQ | WhatsApp: +60169059789 | Why Choose Dexter?