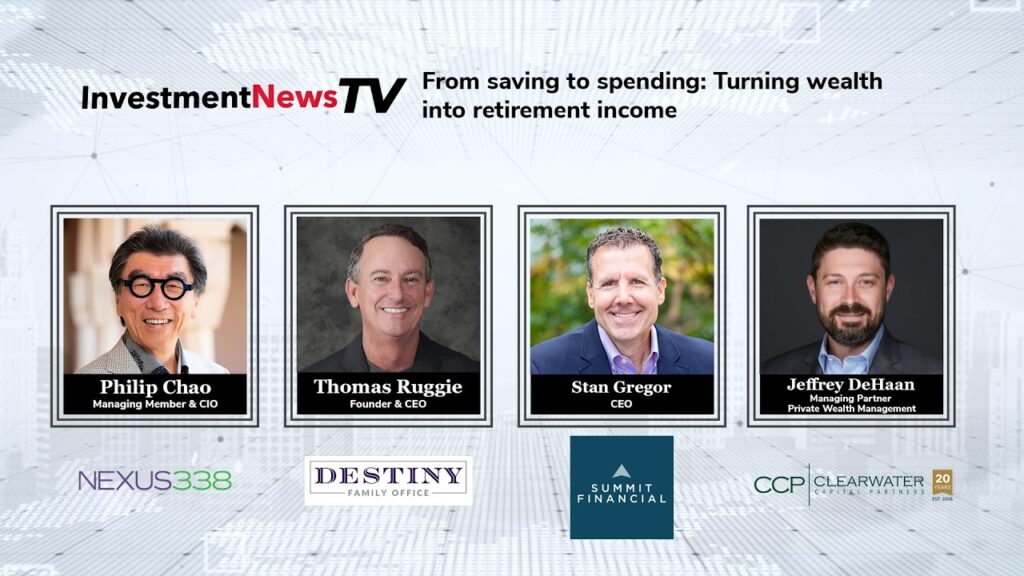
Retirement is a topic many Malaysians are searching for right now, and it’s easy to see why. A recent InvestmentNews panel of financial advisers discussed a problem that often shows up in their client meetings: people have built up savings over decades, but they struggle to turn that wealth into a steady income they feel confident spending. This post explains those ideas in plain language and shows how they apply to your EPF/KWSP savings and other retirement money.
Why do people with savings still hold back from spending them?
Jeffrey DeHaan, managing partner at Clearwater Capital Partners, said that before World War II, retirement “really wasn’t a thing anywhere.” That means most families have had little time to learn how a long retirement is supposed to work. Many feel they are figuring it out as they go.
The same reasoning applies in Malaysia. A long retirement that is funded from a lump of savings is a relatively new challenge for households, so it’s normal to feel uncertain about how much you can safely use each month.
What is longevity risk and why should it worry you?
The panel described longevity risk as the risk of living longer than expected, so your savings have to stretch further. Philip Chao, managing member and CIO of Nexus 338, said that living longer is a widely discussed concern, and he cited a statistic he believed: that babies born this decade have a 50% chance of living to age 100. He also recalled that when Social Security first began, average life expectancy was around 66, though he was not certain of that exact figure.
The lesson is simple. If your savings must support you for 25 or 30 years rather than a short period, a plan built on short-term assumptions can run short. Ask yourself: what happens to my plan if I live well into my 90s?
How can you make your EPF savings last?
The panel stressed that good planning does not assume a perfect scenario. Jeffrey DeHaan explained that his firm stress-tests plans, because things will not go the way we expect and life events and market events both happen. Here is a practical way to apply that thinking to your own money:
- Know your starting point. Check your latest EPF/KWSP statement through your KWSP account and list your other retirement savings and investments.
- Estimate your retirement spending. Write down what you expect to spend each month, including housing, healthcare, food, transport and family support.
- Stress-test the plan. Ask what happens if markets fall, if medical bills rise, or if you live longer than planned. Try a few scenarios, not just one.
- Identify the gap. Compare your expected income with your expected spending. The difference is what your other savings, insurance or planning must cover.
- Review regularly. Revisit the numbers each year or after a major life change, so the plan stays realistic.
What should you weigh before choosing a payout option?
The InvestmentNews discussion did not cover EPF/KWSP payout options, so I am not going to describe their features or terms here. Always check the current rules directly with KWSP. What the panel did offer is a useful way to frame the decision. Stan Gregor, CEO of Summit Financial, suggested that the closer you get to a guarantee, the more you may give up in growth potential. In other words, certainty usually comes with a trade-off.
Before you choose, consider these questions:
- How much monthly income do I need? Start from your spending estimate, not from the amount you hope to receive.
- What if I live longer than planned? Make sure the option still works in your later years.
- How much flexibility do I need? Consider whether you may need lump sums for emergencies or medical costs.
- What do I want to leave behind? Stan Gregor noted that financial planning also prepares the next generation. Think about what your family may inherit.
- What are the costs and conditions? Confirm all terms with KWSP and any other provider before committing.
Should you get professional help with retirement planning?
Thomas Ruggie, founder and CEO of Destiny Family Office, described the core job of a planner as making sure clients do not run out of money in retirement. A good adviser can help you model scenarios and explain trade-offs, but the decisions remain yours. I’m Dexter Chia, a licensed remisier with M+ Global (R336). This post is general education, not personal financial advice. For advice tailored to your situation, speak with a licensed financial planner who can review your full picture.
Frequently Asked Questions
Does the InvestmentNews panel talk about EPF or KWSP?
No. The panel discussed retirement income strategies in general, including longevity risk and how advisers help clients spend their savings. The ideas here are general and have been applied to Malaysian savings for explanation only.
What is longevity risk in simple terms?
It is the risk that you live longer than your savings can support. The panel said living longer is a growing concern, which is why retirement plans need to be tested against long lifespans.
Should I check my KWSP statement before choosing a payout option?
Yes. Your current balance is the starting point for any retirement income plan. Once you know it, estimate your monthly spending and compare it with what each option could provide, after confirming the terms with KWSP.
Source: InvestmentNews