KJTS Group Berhad has convinced Malacca Securities that its strong 2Q26 revenue of RM88.2 million can be matched or beaten in the second half of 2026, lifting the research house’s conviction on the industrial cooling and energy services player. Following the company’s results briefing, Malacca Securities raised its FY27 and FY28 earnings forecasts by 7.3% and 7.2% respectively, and hiked its target price to RM1.32 from RM1.23.
What KJTS Group Does
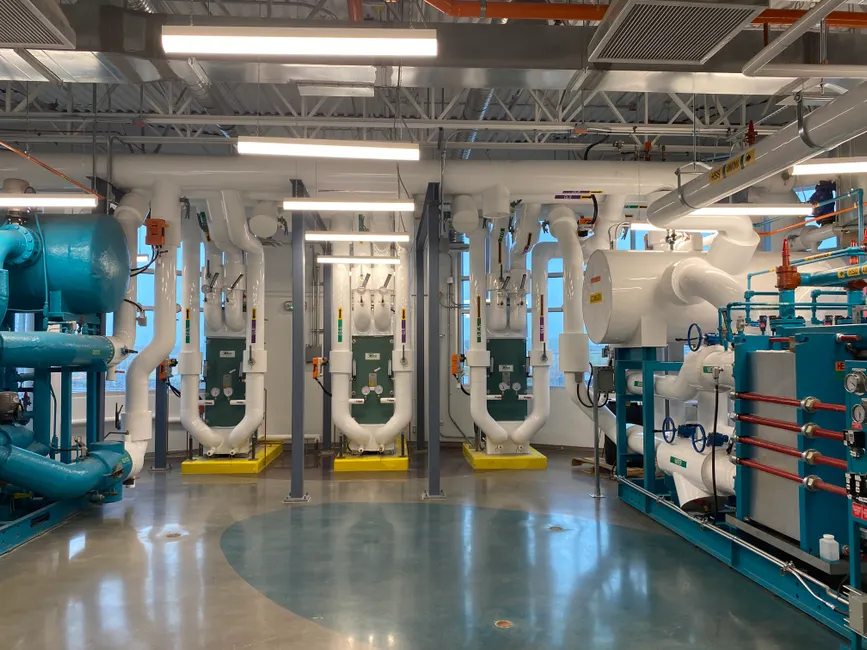
KJTS Group is a Malaysian-listed player focused on engineering, procurement, construction and commissioning (EPCC) projects alongside operations and maintenance (O&M) contracts. The group operates primarily across Thailand and Indonesia, with growing exposure to data centres, hospitals, and manufacturing sectors.
The company is progressively expanding beyond traditional cooling systems into what management calls Utilities-as-a-Service—bundling energy and water-efficiency solutions for customers seeking integrated resource management.
Revenue Momentum and Project Pipeline Strength
Management’s confidence rests on two pillars: ongoing EPCC project execution and the conversion of completed projects into visible, recurring income streams. Malacca Securities noted that 3Q26 and 4Q26 revenue can potentially match or exceed RM88.2 million, with support from continued progress on Thai and Indonesian sites.
KJTS‘s consolidated pipeline stands above RM1.6 billion, a fortress figure that includes approximately RM700 million in opportunities tied to the Stonepeak initiative—deployable over the next 1–2 years. According to Malacca Securities, one larger Stonepeak project has already progressed beyond the ESCO (Energy Services Company) audit stage, signalling real near-term conversion potential.
The research house flagged that several projects are nearing completion and transition into O&M, which typically carry higher and more predictable margins than project work. Recent contract wins with Centel further demonstrate the group’s ability to convert wins into longer-duration recurring income arrangements.
Earnings Forecasts and Valuation Basis
Malacca Securities maintains its FY26 earnings forecast at RM26.6 million but revised upward: FY27 to RM30.4 million (up 7.3%) and FY28 to RM33.4 million (up 7.2%). The upgrades reflect improved visibility on recurring income conversion and pipeline replenishment in the energy services business.
The raised target price of RM1.32 is based on applying a 30x P/E multiple to FY27 EPS of 4.41 sen. According to the research house, this implies 16.8% upside from the time of the briefing. The valuation assumes no change in the P/E multiple, only an upgrade to the earnings base.
Malacca Securities noted that the recurring earnings bridge into FY27–FY28 should provide “greater comfort” on underlying momentum, though project timing remains a material execution variable.
Key Risks to Watch
The research house flagged three downside risks: KJTS’s inability to replenish its order book once current projects conclude, changes to TNB tariff policies (affecting energy cost pass-throughs), and potential contract terminations by customers. Project timing delays are also implicit—pipeline value means nothing if awards slip.
Malacca Securities maintains its BUY call on the assumption that management can execute on conversion timelines and continue winning new mandates at a pace that sustains growth through FY28 and beyond.
What This Means for Retail Investors
KJTS sits at a inflection point: from a project-driven business with lumpy cash flows toward a hybrid model anchored by recurring O&M income. That shift typically supports higher and more stable valuations, provided execution delivers. The RM1.6 billion pipeline and Stonepeak opportunities offer growth visibility into 2027–2028, but conversion is not guaranteed.
For holders, the raised FY27–FY28 forecasts and target price offer reassurance that near-term revenue can sustain or grow. For prospective investors, the 16.8% upside assumes the stock has not already repriced on the briefing; checking the entry point against recent trading history is prudent.
The data centre, hospital, and utilities angle is topical—rising AI infrastructure demand and Southeast Asia’s energy transition could create tailwinds. However, execution risk on EPCC projects and tariff dependency remain real, and the market will be watching quarterly pipeline replenishment closely.
Key Takeaways
- Revenue sustainability: Malacca Securities expects H2 2026 revenue to match or exceed RM88.2m per quarter, supported by EPCC progress and O&M transitions.
- Earnings upgrades: FY27 and FY28 forecasts raised 7.3% and 7.2% to RM30.4m and RM33.4m, reflecting improved recurring income visibility.
- Pipeline strength: RM1.6bn consolidated pipeline includes RM700m Stonepeak opportunities deployable over 1–2 years; one project already past audit stage.
- Valuation call: Malacca Securities maintains BUY with target price raised to RM1.32, implying 16.8% upside based on 30x FY27 P/E.
- Key risks: Order book replenishment, TNB tariff changes, and contract termination risk remain material execution variables to monitor.
Full report available from M+ Online (Malacca Securities). Published 4 September 2026.
Source & Attribution
This article summarises a research report published by Malacca Securities Sdn Bhd (M+ Online) on 04 September 2026. All ratings, target prices and forecasts belong to Malacca Securities Research, not to the author of this blog.
Read the original report: M+ Online Research Report | View full PDF
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice or a recommendation to buy or sell any security. Ratings and target prices cited are those of Malacca Securities Research and are subject to change. Always do your own research before making investment decisions.
Want access to full M+ Online research reports and AI stock analysis? Contact Dexter Chia, AI-Driven Remisier at Malacca Securities Sdn Bhd. M+ Global Invitation Code: UBZQ | WhatsApp: +60169059789 | Why Choose Dexter?