Energy Services Surge Lifts Half-Year Earnings 45%
KJTS Group Berhad delivered a stronger-than-expected first-half 2026 performance, with core PATMI climbing 45.2% year-on-year to RM12.7m, according to Malacca Securities Research. The 2Q26 result was particularly robust: core PATMI surged 75.4% quarter-on-quarter and 79.3% year-on-year to RM8.1m, accounting for 63.4% of the research house’s full-year FY26 earnings forecast of RM20.0m.
The standout driver was Energy Services revenue, which jumped 95.7% quarter-on-quarter to RM68.7m following the commencement of recently secured contracts. Total group revenue surged 57.7% to RM88.2m in 2Q26, while Integrated Facilities Management revenue declined 6.2% to RM19.5m after the expiry of several cleaning services contracts.
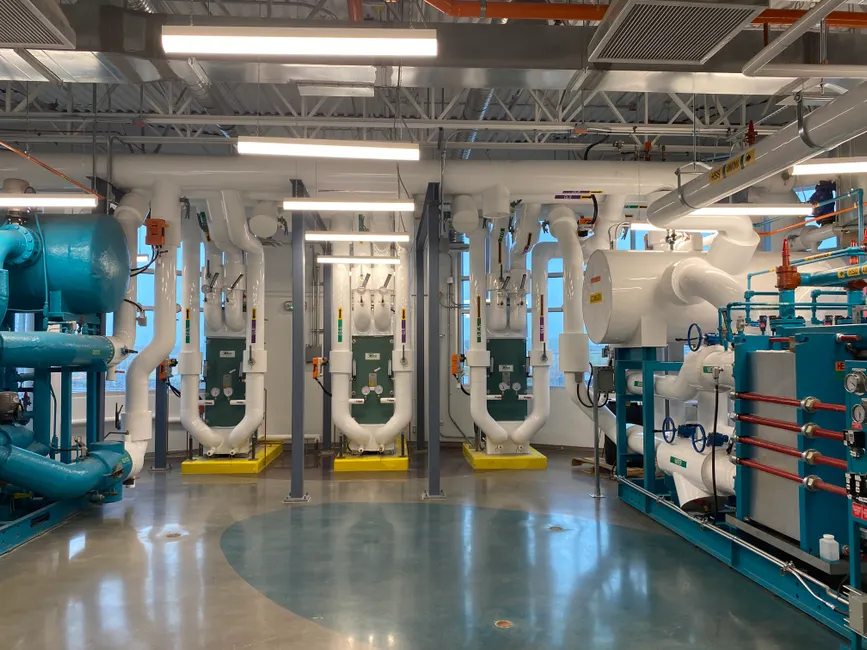
What KJTS Group Does
KJTS Group operates across two segments: Energy Services and Integrated Facilities Management. The Energy Services division focuses on energy-efficient cooling infrastructure and chiller rental solutions, areas that align with Malaysia’s energy transition policies and data centre demand growth.
The Integrated Facilities Management arm provides cleaning and facility maintenance services, though this segment is now a minority contributor to overall earnings. Last year, KJTS completed the acquisition of iHandal, broadening its energy-services capability into heat-recovery solutions and creating cross-selling opportunities, according to Malacca Securities.
The Financial Picture: Earnings Beat Driven by Margin Expansion
Year-to-date 1H26, group revenue expanded 59.0% to RM144.1m, while profit before tax (PBT) grew at a faster clip of 75.9% to RM17.7m. This earnings acceleration reflects the disproportionate contribution from higher-margin Energy Services contracts.
Energy Services accounted for 77.9% of 2Q26 group revenue versus 55.3% a year ago, signalling a structural shift in the business mix. Malacca Securities noted that 2Q26 profit margins improved: PBT margin expanded 1.6 percentage points and core PATMI margin rose 1.0 percentage point, despite higher administrative expenses.
However, the research house flagged a higher effective tax rate (ETR). The 1H26 ETR was 26.3%, compared to 12.6% in 1H25, which moderates reported earnings growth. 2Q26 saw an ETR of 24.3% versus 15.4% in the prior-year quarter.
Valuation and Forward Outlook
Malacca Securities maintains a target price of RM0.87 for KJTS, though the research house noted that valuation is under review pending the upcoming earnings briefing. The research house made no changes to its FY26–FY27 earnings forecasts at the time of publication, but signalled scope to revisit both earnings assumptions and the valuation base after management guidance becomes available.
According to Malacca Securities, KJTS benefits from three key structural tailwinds: (i) sustained demand for energy-efficient cooling infrastructure driven by Malaysia’s energy transition agenda, (ii) MIDA’s RM92.8bn of approved investments, including RM34.6bn across data centre and cloud-computing projects, which provides forward demand visibility, and (iii) the iHandal acquisition’s ability to broaden recurring income.
Key Risks and Constraints
Malacca Securities identified three material downside risks to its recommendation. First, KJTS’s inability to replenish its orderbook post-contract execution could constrain future revenue visibility. Second, changes in TNB’s (Tenaga Nasional Berhad) tariff policies could alter customer demand patterns or contract economics.
Third, potential contract terminations from major customers represent an execution risk. Given that Energy Services now represents the bulk of earnings, customer concentration and contract sustainability are factors retail investors should monitor closely via quarterly results updates and investor briefings.
What This Means for Retail Investors
KJTS Group has demonstrated tangible earnings momentum driven by a genuine shift toward higher-margin energy services contracts. The data centre and energy transition tailwinds cited by Malacca Securities — specifically MIDA’s RM34.6bn in approved data centre investments — suggest a multi-year growth runway rather than a cyclical spike.
However, the higher 1H26 ETR also signals that headline earnings growth may be moderating on a tax-normalised basis, something to bear in mind when projecting future returns. The research house’s willingness to revisit earnings forecasts and valuation post-briefing suggests the RM0.87 target price may not be the final word — retail investors should await management guidance on contract visibility and medium-term margin sustainability before making allocation decisions.
The full Malacca Securities research report is available on M+ Online at the link above.
Key Takeaways
- KJTS posted 1H26 core PATMI of RM12.7m, up 45.2% YoY, driven by Energy Services revenue surge of 95.7% QoQ to RM68.7m.
- Energy Services now represents 72% of group revenue (1H26) versus 56.5% a year ago, indicating a structural earnings mix shift toward higher-margin contracts.
- Malacca Securities maintains a target price of RM0.87 but signalled valuation is under review pending upcoming earnings briefing and management guidance on sustainability of earnings momentum.
- MIDA’s RM34.6bn in approved data centre investments provides multi-year demand visibility for KJTS’s energy services and cooling infrastructure solutions.
- Key downside risks include orderbook replenishment risk, TNB tariff policy changes, and potential customer contract terminations — factors to monitor via quarterly updates.
Source & Attribution
This article summarises a research report published by Malacca Securities Sdn Bhd (M+ Online) on 28 August 2026. All ratings, target prices and forecasts belong to Malacca Securities Research, not to the author of this blog.
Read the original report: M+ Online Research Report | View full PDF
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice or a recommendation to buy or sell any security. Ratings and target prices cited are those of Malacca Securities Research and are subject to change. Always do your own research before making investment decisions.
Want access to full M+ Online research reports and AI stock analysis? Contact Dexter Chia, AI-Driven Remisier at Malacca Securities Sdn Bhd. M+ Global Invitation Code: UBZQ | WhatsApp: +60169059789 | Why Choose Dexter?