Turnaround Story Gains Traction: 3QFY26 Core PATMI Swings to RM7.2m Profit
EITA Resources Bhd posted a core net profit attributable to minority interests (PATMI) of RM7.2 million in 3QFY26, a dramatic turnaround from a net loss of RM0.4 million in the same quarter a year ago. This recovery was led by the Manufacturing segment, which swung to a profit of RM2.4 million in 3QFY26 from a loss of RM3.0 million in 3QFY25—a RM5.4 million pre-tax profit turnaround.
The quarterly performance was powered by a 66.9% surge in Manufacturing revenues, predominantly driven by Busduct deliveries for Indonesia data centre infrastructure projects. Despite the strong quarter, nine-month core PATMI for FY26 sits at RM11.5 million, down 7.6% year-on-year from RM12.4 million in 9MFY25, reflecting the uneven earnings contribution across segments.
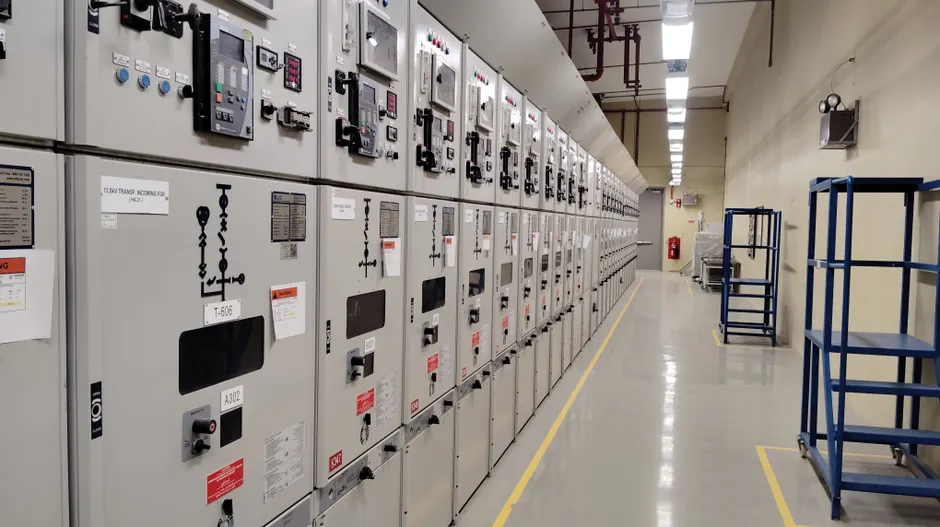
What EITA Resources Does: Busduct, High-Voltage Systems, and Infrastructure Services
EITA operates across three main segments: Manufacturing (focused on Busduct systems for data centre power distribution), the High-Voltage (HV) segment (electrical infrastructure), and Marketing & Distribution plus Services (ancillary revenue streams). The company has emerged as a regional supplier of Busduct systems to hyperscale data centre operators, positioning it at the intersection of rapid Southeast Asian data centre expansion.
The group’s 60%-owned subsidiary, TransSystem Continental, will execute the RM221.0 million SESCO Mapai 500kV substation project in Sarawak over 25 months, commencing 7 September 2026. This marks EITA’s first 500kV substation project in Sarawak, with an estimated gross profit margin of 13%, contributing approximately RM17.2 million to EITA’s bottom line over the contract duration.
Raising Forecasts: FY26–FY28 Earnings Upgraded 24.2%, 14.5%, 16.5%
According to Malacca Securities Research, the research house raised its core PATMI forecasts for FY26, FY27, and FY28 to RM19.0 million, RM22.9 million, and RM25.4 million respectively, representing upgrades of 24.2%, 14.5%, and 16.5% from previous projections of RM15.3 million, RM20.0 million, and RM21.8 million.
The FY26 uplift assumes stronger Busduct execution in the final quarter, with concurrent contributions from both Indonesia and Johor Busduct projects. Management expects 4QFY26 to outperform 3QFY26, with operational momentum extending into the first half of FY27. By end-2026, the group’s outstanding orderbook is targeted to reach RM1.0 billion, up substantially from RM423.9 million as of 30 June 2026.
HV Segment Path to Breakeven: Losses to Narrow in FY27, Turn Operational Breakeven in FY28
The HV segment remains a drag on earnings but is showing signs of stabilization. Management guidance indicates the HV segment will remain loss-making in FY27, but losses will narrow significantly as project execution accelerates, with the unit reaching operational breakeven in FY28. This pathway is critical because narrowing HV losses will reduce unabsorbed tax losses and normalize the group’s elevated effective tax rate, unlocking higher net profit conversion at the bottom line.
The improving mix—higher-margin Busduct orders offset by reduced HV drag—provides what Malacca Securities termed “multi-year earnings visibility” anchored by a RM1.0 billion orderbook by year-end.
Valuation Basis: 11.0x P/E Multiple on Revised FY27 EPS
Malacca Securities maintains a BUY call with a target price of RM0.83 (revised up from RM0.69). The target is derived using an 11.0x price-to-earnings multiple applied to revised FY27 forward earnings per share (EPS) of 7.57 sen. This valuation reflects the research house’s confidence in near-term earnings acceleration and the RM1.0 billion orderbook visibility extending into FY27 and FY28.
The upgrade from Hold to Buy signals Malacca Securities’ view that the combination of Busduct momentum and HV cost rationalization justifies a premium to the group’s historical trading range. No downside target or bear case valuation was explicitly disclosed in the research summary.
Risk Factors: Execution Risk and Data Centre Capex Cycles
Key risks flagged include project execution delays on the RM221.0 million Mapai substation and large Busduct orders; economic slowdown impacting regional data centre capital expenditure cycles; and intensity of competition in Busduct manufacturing from lower-cost regional suppliers. Currency headwinds on Indonesian operations and supply chain disruptions were not explicitly mentioned but are implicit in offshore manufacturing exposure.
The SESCO Mapai project, while substantial, is a single large contract; concentration risk exists if orderbook growth cannot sustain beyond current projects. Management’s FY27 HV segment loss guidance also carries execution risk—if project ramp-up falters, the path to FY28 breakeven may slip.
What This Means for Retail Investors
For retail investors, EITA’s earnings recovery is real but dependent on two moving parts: sustained Busduct order wins (cyclical data centre demand) and actual HV segment loss containment (execution-dependent). The RM1.0 billion orderbook target by year-end, if achieved, provides transparency into forward revenue visibility—a positive sign for long-term planning. However, the company remains exposed to data centre capex cycles, which are macroeconomically sensitive and can slow with interest rate hikes or tech sector retrenchment.
The RM0.83 target price from Malacca Securities implies meaningful upside from recent trading levels, conditional on delivery of 4QFY26 results and orderbook expansion announcements. Retail investors should monitor quarterly cash flow generation (not just accounting profits), progress on the Mapai project, and HV segment loss trends in upcoming quarterly results.
For the full Malacca Securities research report, visit M+ Online.
Key Takeaways
- 3QFY26 core PATMI of RM7.2m represents a decisive turnaround, driven by Manufacturing segment swing from RM3.0m loss (3QFY25) to RM2.4m profit, underpinned by 66.9% revenue surge in Busduct.
- FY26–FY28 core PATMI forecasts raised 24.2%, 14.5%, 16.5% to RM19.0m, RM22.9m, RM25.4m respectively, reflecting Busduct momentum and HV segment rationalization.
- RM1.0 billion orderbook target by end-2026 (vs. RM423.9m at 30 June 2026) provides multi-year revenue visibility across Busduct, HV infrastructure, and the RM221m Mapai substation contract.
- Malacca Securities upgraded to BUY with RM0.83 target price (from Hold at RM0.69), valuing the stock at 11.0x FY27f EPS of 7.57 sen.
- HV segment losses expected to narrow in FY27 and turn operationally breakeven in FY28, reducing unabsorbed tax losses and improving group net profit conversion.
Source & Attribution
This article summarises a research report published by Malacca Securities Sdn Bhd (M+ Online) on 08 September 2026. All ratings, target prices and forecasts belong to Malacca Securities Research, not to the author of this blog.
Read the original report: M+ Online Research Report | View full PDF
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice or a recommendation to buy or sell any security. Ratings and target prices cited are those of Malacca Securities Research and are subject to change. Always do your own research before making investment decisions.
Want access to full M+ Online research reports and AI stock analysis? Contact Dexter Chia, AI-Driven Remisier at Malacca Securities Sdn Bhd. M+ Global Invitation Code: UBZQ | WhatsApp: +60169059789 | Why Choose Dexter?