Aumas Resources Berhad is poised to unlock significant production gains as it nears completion of a new processing facility that will shatter its existing bottleneck, according to research published by Malacca Securities on 26 August 2026. The 2,000 tpd processing plant at Bukit Mantri—expected operational in 1HFY27—represents a transformational capex that more than doubles current throughput of approximately 1,200 tpd, addressing a constraint that has capped gold output despite abundant in-situ mineral resources.
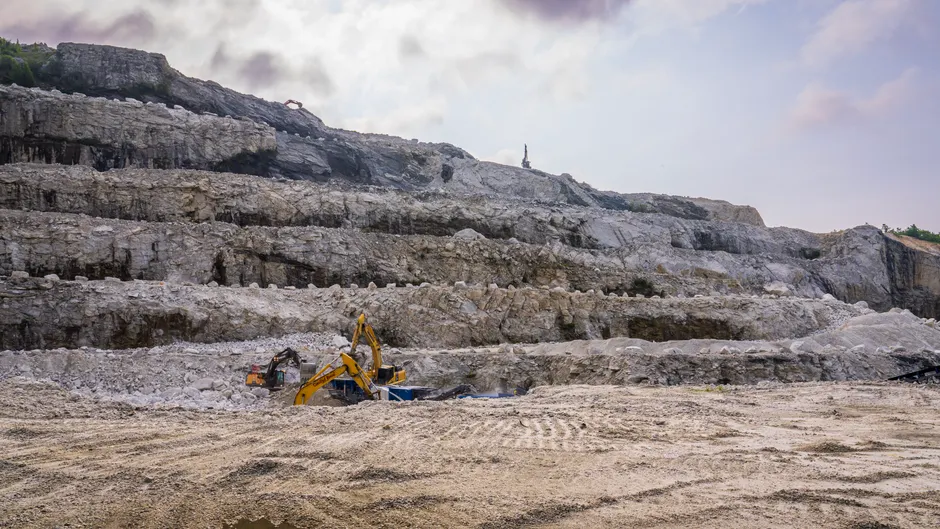
What Aumas Does and Why Metals Matter Now
Aumas Resources operates primarily in gold and silver mining, with production centred at its Bukit Mantri concession in Peninsular Malaysia. The commodity backdrop is working in the group’s favour: gold rebounded above USD4,600/oz amid geopolitical tensions, while silver traded toward USD68.0/oz, translating directly into improved average selling prices (ASP) for the miner.
According to Malacca Securities Research, elevated precious metals valuations combined with imminent capacity additions create a dual tailwind for production growth and margin expansion. The research house noted that this confluence of higher commodity prices and operational leverage has historically driven cyclical upside for junior gold producers trading on Bursa Malaysia.
Capacity Expansion and Resource Upside
The Bukit Mantri processing plant expansion is the headline catalyst. The new 2,000 tpd facility will increase milling throughput by 67% above current levels, removing the processing constraint that has historically limited gold recovery from available ore in the pit. Malacca Securities expects the plant to transition to commercial operation in the first half of FY27.
Equally material is the Mount Andrassy exploration partnership with Aurelius Borneo Mining, where Aumas holds a 70% profit-sharing stake across an 18,000-hectare concession roughly 10 km from Bukit Mantri. M+ Online’s research team projects that geological mapping and initial exploratory drilling currently underway could delineate significant gold-bearing ore bodies, potentially extending mine life well beyond the existing Bukit Mantri footprint and mitigating depletion risk.
Technical Setup and Price Targets
On the technical side, Malacca Securities identified bullish divergence signals in the stock’s price action, signalling a potential breakout scenario. The research house flagged next resistance levels at RM0.515 and RM0.585, with support entrenched at RM0.365–RM0.375. A break below support would invalidate the technical setup.
Malacca Securities maintains a BUY call with a RM0.76 target price, implying material upside from current levels. The valuation anchors to the tangible catalysts: capacity addition, rising metal prices, and exploration optionality. The research house’s base case assumes the new plant commissions on schedule and commodity prices remain elevated through the forecast period.
Risks Worth Monitoring
Capital discipline remains paramount. Any capex overruns or delays to the 1HFY27 commissioning target could push out return-on-investment timelines and compress near-term cash generation. Gold and silver prices are inherently cyclical; a sharp pullback in commodity valuations would flow directly through to ASP and mine economics, potentially invalidating the positive thesis.
Exploration risk at Mount Andrassy is real. Geological prospecting and drilling results may disappoint, or ore grades/tonnages may prove insufficient to justify mine development, dampening the mine-life extension narrative. Regulatory and environmental approvals for the new processing facility should also be tracked closely, as permitting delays in Malaysia have historically derailed junior mining projects.
What This Means for Retail Investors
Aumas Resources presents a play on two trends: immediate production leverage from capacity addition and longer-dated optionality from exploration. For growth-oriented retail investors with a moderate risk appetite and a 12–24 month time horizon, the stock offers exposure to a re-rating on operational inflection and commodity upside. However, junior mining equities remain volatile and sensitive to commodity swings and execution risk; position sizing and stop-loss discipline are essential.
The research from Malacca Securities is data-driven and forward-looking, but investors should read the full report on M+ Online before making any investment decision. Past performance and analyst ratings do not guarantee future returns.
Key Takeaways
- Capacity driver: New 2,000 tpd plant (67% above current throughput) expected operational 1HFY27, addressing production bottleneck.
- Commodity tailwind: Gold above USD4,600/oz and silver toward USD68.0/oz improving ASP in a high-price regime.
- Resource upside: Mount Andrassy 18,000-ha concession with 70% profit-sharing stake offers mine-life extension optionality.
- Valuation: Malacca Securities BUY call with RM0.76 target price based on capacity addition, metal prices, and exploration potential.
- Technical confirmation: Bullish divergence signals identified; next resistances at RM0.515 and RM0.585; support at RM0.365–RM0.375.
Full Report: The complete research analysis is available from Malacca Securities (M+ Online) at https://mplusonline.com/research-report/detail/1400
Source & Attribution
This article summarises a research report published by Malacca Securities Sdn Bhd (M+ Online) on 26 August 2026. All ratings, target prices and forecasts belong to Malacca Securities Research, not to the author of this blog.
Read the original report: M+ Online Research Report | View full PDF
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice or a recommendation to buy or sell any security. Ratings and target prices cited are those of Malacca Securities Research and are subject to change. Always do your own research before making investment decisions.
Want access to full M+ Online research reports and AI stock analysis? Contact Dexter Chia, AI-Driven Remisier at Malacca Securities Sdn Bhd. M+ Global Invitation Code: UBZQ | WhatsApp: +60169059789 | Why Choose Dexter?