The research house projects that TMK Chemical‘s illustrative FY2025 pro forma PATAMI could climb 57.6% to RM153.2m once its conditional deal for CCM is completed, according to Malacca Securities Research.
TMK Chemical CCM Acquisition: What Changes
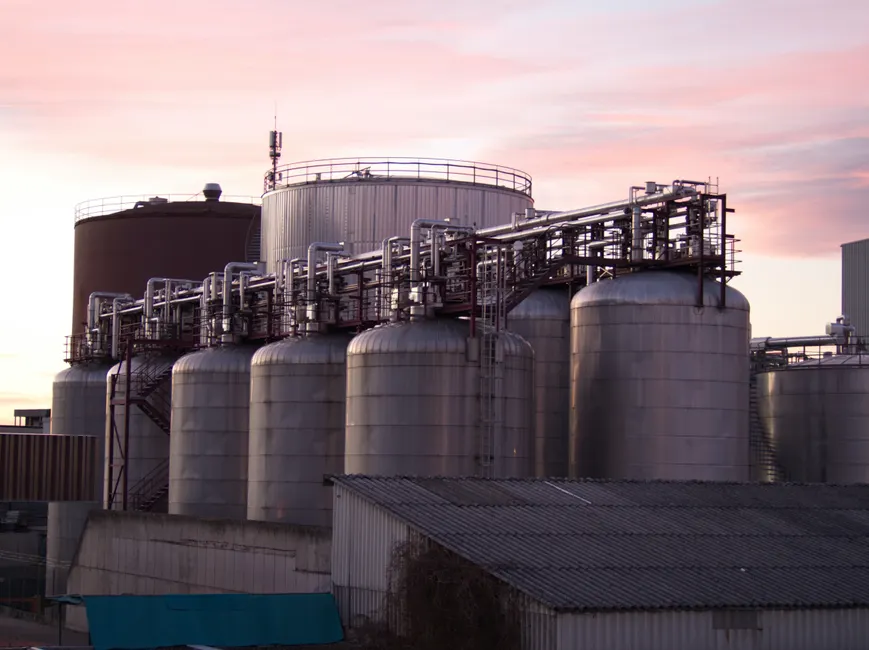
TMK Chemical currently runs chemical trading, storage and logistics operations. The research house argues that pairing these with CCM‘s chlor-alkali manufacturing could improve procurement efficiencies, supply-chain integration and downstream market exposure.
The consideration is RM939.9m, or 12.9x adjusted FY2025 PATAMI. It comprises 262.5m new TMK shares priced at RM1.9098 each and RM438.5m in cash, with RM99.1m from IPO proceeds and the balance from borrowings and/or internal funds. Completion is targeted for 1Q2027, subject to approvals.
Key Financial Numbers
Malacca Securities notes that the illustrative pro forma figures show EPS rising 24.9%, from 9.72 sen on TMK’s existing 1,000m shares to 12.14 sen on the enlarged 1,262.5m share base. That increase holds despite the issuance of 262.5m new shares.
CCM’s own earnings are softer, with 9MFY2026 net profit falling 20.7% year on year to RM44.3m. The research house says this warrants a reassessment of sustainable earnings, even as TMK’s standalone 1HFY2026 core PATAMI rose 68.7% to RM71.0m.
Malacca Securities forecasts core earnings of RM149.4m in FY26f, RM235.2m in FY27f and RM274.9m in FY28f. It expects CCM to contribute RM45.3m over nine months in FY27f and RM70.0m in FY28f, assuming completion by end-March 2027.
The demand backdrop is supportive, according to the research house. Malaysia’s industrial production index grew 5.0% year on year in August 2026, with manufacturing up 7.4% and the petroleum, chemical, rubber and plastic products subsector up 2.6%. Manufacturing sales rose 9.9% to RM185.0bn.
Capacity growth is also on the table. Banting Plant 2, scheduled for 2027, is expected to add 40,000 ECU and double TMK’s existing chlor-alkali derivatives capacity at roughly 60% lower capital investment. Malacca Securities also cites rare-earth projects, including a Lynas facility planned for 5,000 tonnes of feedstock annually and a Carester-Malaco project in Perak that could add up to 13,000 tonnes of processing capacity, as potential demand drivers for HCl and caustic soda.
Valuation Basis Behind the RM3.27 Target
Malacca Securities maintains its HOLD rating and raises its target price to RM3.27 from RM2.86. The target is based on an unchanged 15.0x P/E applied to FY28f EPS of 21.77 sen, implying 2.5% upside from RM3.19.
The research house rolled its valuation forward to FY28f because that year captures the first full year of CCM’s earnings contribution. Its EPS forecasts are based on the enlarged share base of 1.2625bn shares.
Risks Flagged by the Research House
Malacca Securities lists six downside risks: non-completion of the conditional share sale and purchase agreement, higher-than-expected debt funding or share issuance, integration risk, commodity and raw material cost volatility, potential environmental liabilities, and regulatory and non-interested shareholder approval risks.
The report also flags that TMK’s projected public shareholding spread of 17.9% falls below its approved 21% minimum. A compliance solution will be needed alongside the regulatory approvals.
What This Means for Retail Investors
The projected earnings uplift depends on CCM completing by end-March 2027, so timing matters for the FY2027 numbers. Retail holders should also weigh the dilution, since the share count rises from 1,000m to 1,262.5m.
This article summarises the research house’s views and does not constitute investment advice. The full report, including its assumptions and sensitivity details, is available from M+ Online at mplusonline.com/research-report/detail/1498.
Key Takeaways
- Malacca Securities keeps a HOLD call on TMK Chemical with a target price of RM3.27.
- The RM939.9m CCM deal equals 12.9x adjusted FY2025 PATAMI.
- Illustrative pro forma PATAMI rises 57.6% to RM153.2m, while EPS rises 24.9% to 12.14 sen.
- CCM’s 9MFY2026 net profit fell 20.7%, which the research house says needs reassessment.
- The public shareholding spread of 17.9% sits below the 21% minimum.
Frequently Asked Questions
What is Malacca Securities’ target price for TMK Chemical?
Malacca Securities maintains a HOLD call on TMK Chemical with a target price of RM3.27, raised from RM2.86. The target implies 2.5% upside from the reference price of RM3.19 and is based on a 15.0x P/E applied to FY28f EPS of 21.77 sen.
How much is TMK Chemical paying for CCM?
TMK Chemical is paying RM939.9m for 100% of CCM, equivalent to 12.9x adjusted FY2025 PATAMI, according to Malacca Securities. The consideration is split between 262.5m new shares and RM438.5m in cash, with completion targeted for 1Q2027.
Will the CCM deal dilute TMK Chemical’s earnings per share?
The research house projects that EPS would rise 24.9% on an illustrative FY2025 pro forma basis, from 9.72 sen to 12.14 sen, despite the 262.5m new shares. Malacca Securities forecasts EPS of 18.63 sen in FY27f and 21.77 sen in FY28f.
📊 On AI Stock Terminal: TMK quarterly results · TMK announcements
Source & Attribution
This article summarises a research report published by Malacca Securities Sdn Bhd (M+ Online) on 10 November 2026. All ratings, target prices and forecasts belong to Malacca Securities Research, not to the author of this blog.
Read the original report: M+ Online Research Report | View full PDF
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice or a recommendation to buy or sell any security. Ratings and target prices cited are those of Malacca Securities Research and are subject to change. Always do your own research before making investment decisions.
Want access to full M+ Online research reports and AI stock analysis? Contact Dexter Chia, AI-Driven Remisier at Malacca Securities Sdn Bhd. M+ Global Invitation Code: UBZQ | WhatsApp: +60169059789 | Why Choose Dexter?