The A1H IPO is the first real test of what the RM5.68bil purchase of Ramsay Sime Darby Health Care Sdn Bhd (RSDH) created. Some estimates put A1H at about RM30bil, and the draft prospectus shows why that number needs scrutiny.
What Is the A1H IPO Valuation Question?
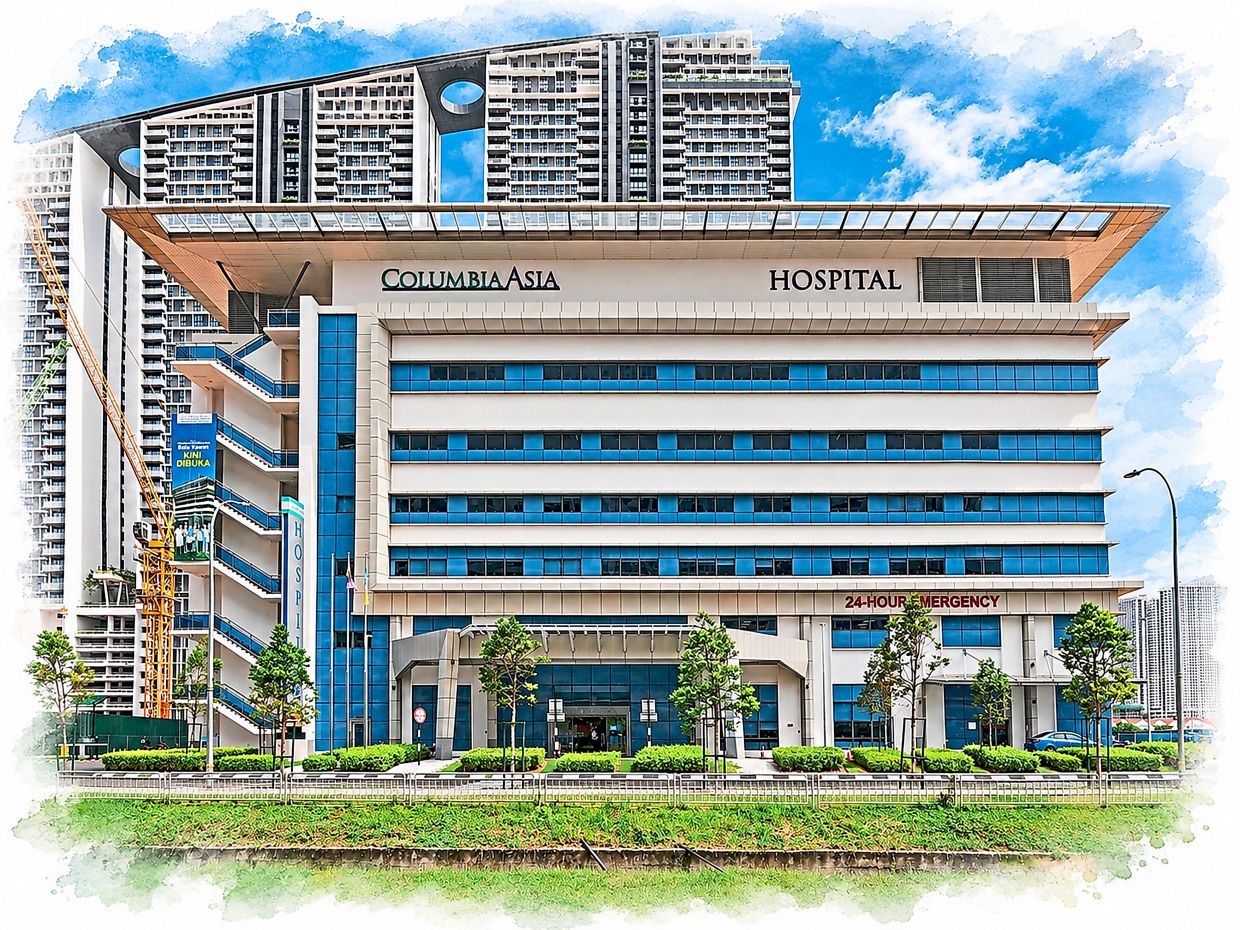
A1H’s listing will show how much value the enlarged hospital group has created. Investors must weigh that against pressure on treatment costs and medical inflation.
A1H operates 23 hospitals: 22 in Malaysia and one in Vietnam. The three Indonesian hospitals bought in the RSDH deal are not part of the listing.
Why Did the RSDH Deal Raise Pricing Questions?
At end-2023, Columbia Asia Healthcare Sdn Bhd bought RSDH from Sime Darby Bhd and Ramsay Health Care Ltd for RM5.68bil cash. The buyer was then indirectly owned by Hong Leong Group and TPG-managed funds, and was renamed A1H in May 2024.
The price implied an enterprise value (EV) of RM6.06bil, or 20.1 times Ebitda for the financial year ended June 2023. It followed competitive bidding and included full control.
- Malaysian hospitals retained: Subang Jaya Medical Centre, Ara Damansara Medical Centre, Bukit Tinggi Medical Centre and ParkCity Medical Centre
- TE Asia transaction (August 2024): majority interests in ALTY Orthopaedic Hospital, Beacon Hospital, Cardiac Vascular Sentral Kuala Lumpur, Hospital Picaso and Northern Heart Hospital Penang
Comparing the eventual market value with RM5.68bil would need to include later acquisitions and capital invested.
What Do A1H’s FY26 Earnings Show?
- FY26 Ebitda (year ended March 2026): RM899.5mil
- FY26 adjusted Ebitda: RM970.4mil, after adding back mainly employee and doctors’ share-based payments
- FY25 supplementary adjusted Ebitda: RM912.3mil, assuming TE Asia contributed 12 months versus eight in the combined figures
- Growth: approximately 6.4%
Both FY26 figures include contributions from acquired hospitals.
How Does the RM30bil Estimate Compare With Sunway Healthcare?
The article views 20 to 25 times FY26 adjusted Ebitda as a more realistic valuation. The RM30bil estimate implies about 32 times.
- Sunway Healthcare Holdings Bhd: 37.6 times forecast FY26 Ebitda, per RHB Research’s Nov 2 report
- Sunway Healthcare IPO: 36.1 times historical FY24 Ebitda, per its prospectus
- Sunway Healthcare (FY25, per A1H’s draft prospectus): 48.5 times EV/Ebitda
- IHH Healthcare Bhd: 16 times
- KPJ Healthcare Bhd: 13.8 times
RHB Research forecasts Sunway Healthcare’s Ebitda rising from RM657mil in FY26 (ending Dec 31) to RM847mil in FY27, about 29% growth. Sunway’s premium depends on hospital openings, bed count growth and occupancy delivering that jump.
These developments quite likely rule out any potential acquisition plans by IHH Healthcare Bhd at this late stage.
Will DRG Billing and MediAsas Change A1H’s Earnings?
MediAsas, a voluntary medical insurance and takaful plan, is scheduled for nationwide launch in January 2027. Budget 2027 also provides for standardised private hospital billing categories next year.
DRG payments are targeted to begin progressively from January, as a voluntary initiative for private hospitals at inception, based on a Health Ministry spokesperson’s statement at a September press briefing. Hospitals will receive pre-determined payments grouped by diagnosis, procedure and severity.
DRG could pressure private hospital earnings, based on what happened in other countries. More affordable coverage could lift patient volumes, but case-based payments make controlling treatment costs more important.
What Is A1H’s Bed Expansion Target for 2032?
- 470 built beds were not yet licensed or operational as at March 31 this year
- Target: approximately 3,900 beds by March 31, 2032, through brownfield expansion and hospital upgrades
- Under evaluation: 600 to 1,000 additional beds
A1H also plans to upgrade hospitals to increase case acuity and optimise case mix.
Where Are the A1H IPO Details and How Do You Apply?
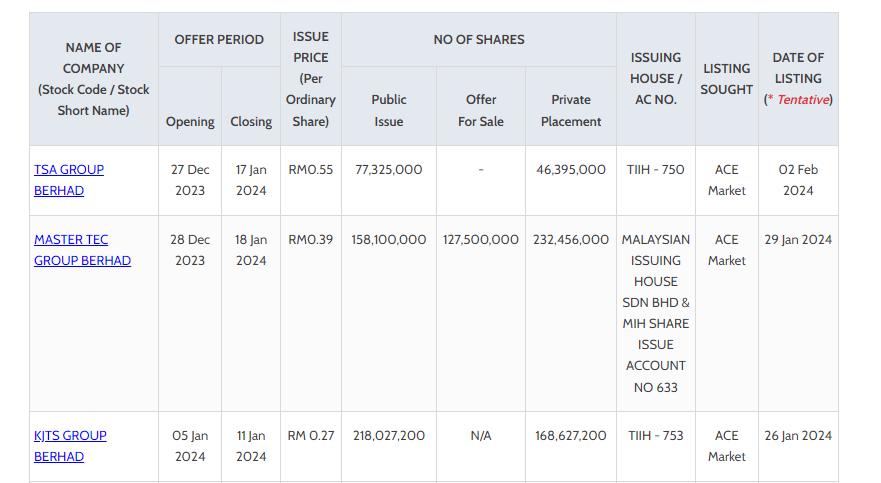
The draft prospectus leaves the offer price and valuation blank. The source material does not yet confirm the listing market, offer size, subscription period or tentative listing date.
Online IPO applications need a direct CDS account in the applicant’s own name, and only one application per IPO is allowed. Read more about IPO Investing with M+ Global.
- Apply through the M+ Global app using Invitation Code UBZQ
- Multiple applications for the same IPO are an offence under the Capital Markets and Services Act 2007
- Retail portions are balloted when the IPO is oversubscribed
- Need help? WhatsApp +60169059789
Key Takeaways
- The offer price, valuation and listing market are not yet announced; RM30bil is an estimate.
- FY26 adjusted Ebitda reached RM970.4mil, up approximately 6.4%.
- The RM30bil estimate implies about 32 times EV/Ebitda, against the article’s 20 to 25 times realistic range and Sunway Healthcare’s 37.6 times forecast.
- DRG and MediAsas from January 2027 are the main earnings wildcards.
📊 On AI Stock Terminal: Malaysia IPO calendar
Disclaimer: This article is general information, not a recommendation to buy, sell or hold any security. Do your own research and read the final prospectus before making any decision.
Frequently Asked Questions
Is the A1H IPO offer price already announced?
No. The draft prospectus leaves the offer price and valuation blank, although some estimates put A1H at about RM30bil.
How much did Columbia Asia pay for RSDH?
Columbia Asia Healthcare Sdn Bhd paid RM5.68bil cash at end-2023. The price implied an enterprise value of RM6.06bil, or 20.1 times Ebitda for the financial year ended June 2023.
What is A1H’s FY26 adjusted Ebitda?
A1H reported adjusted Ebitda of RM970.4mil for the financial year ended March 2026. That is approximately 6.4% higher than the RM912.3mil supplementary FY25 figure.
How do I apply for the A1H IPO?
Once the offer opens, apply through the M+ Global app with Invitation Code UBZQ. You need a direct CDS account in your own name, and only one application per IPO is allowed.
Source: View Original Article — The content is based on the original publisher. Refer to the original content for accurate info. Contact us for any changes.
Related Articles & Resources
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Always do your own research before making investment decisions.
Want to invest in Bursa Malaysia or US markets? Contact Dexter Chia, an AI Driven Remisier who has 2,300+ clients at Malacca Securities Sdn Bhd (M+ Global). M+ Global Invitation Code: UBZQ | WhatsApp: +60169059789 | Why Choose Dexter?